

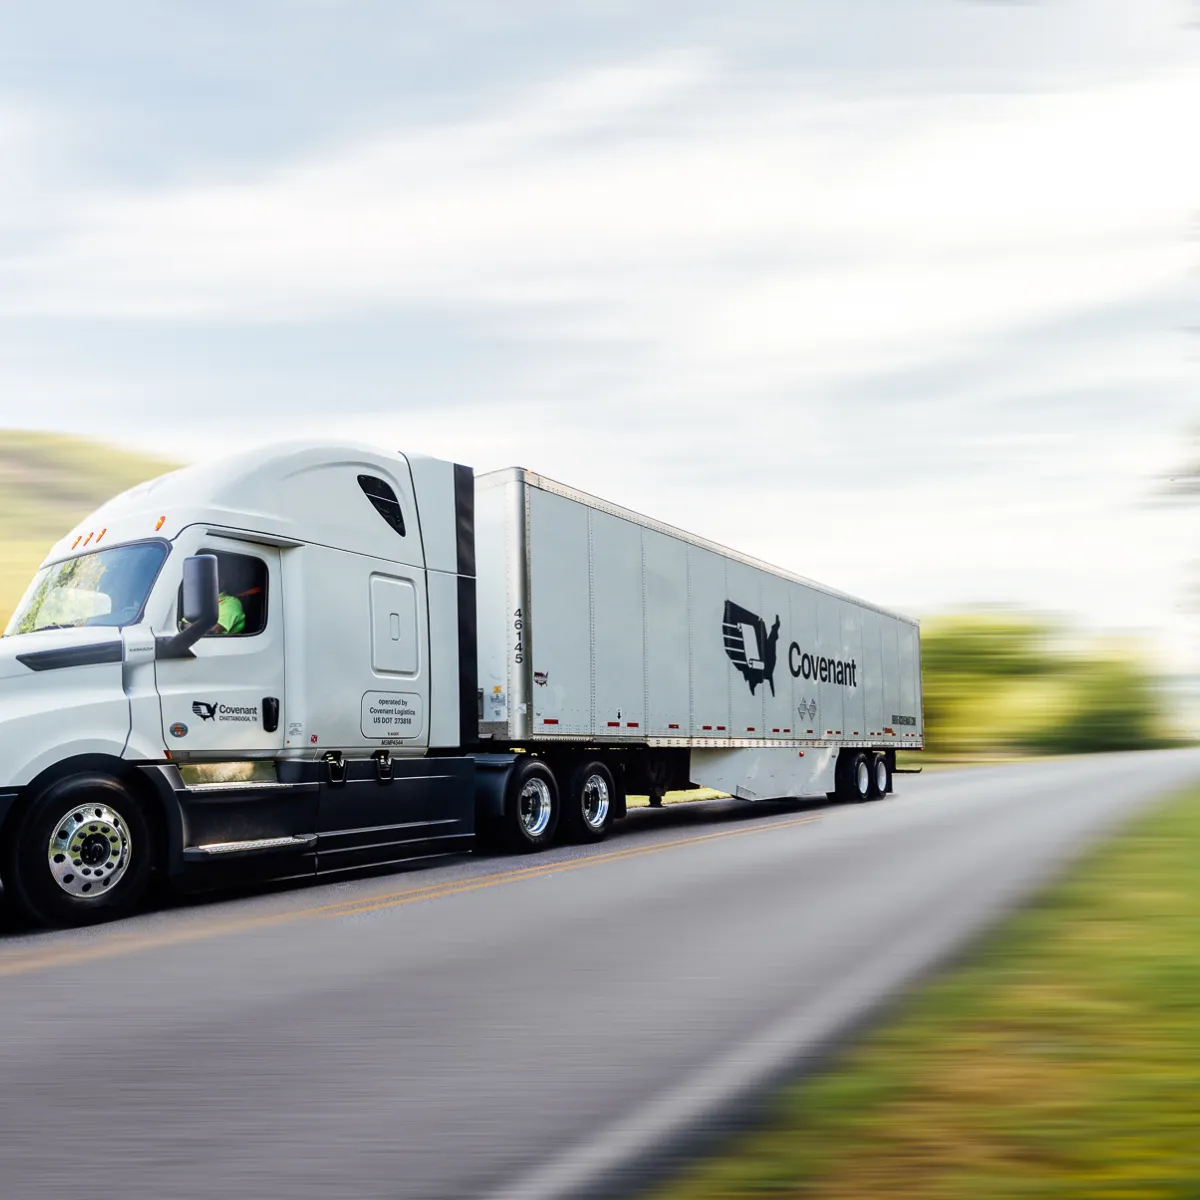
Covenant Logistics Group posted a strong financial performance in the third quarter of 2026, reporting total revenue of $353.9 million, a 19.2% increase compared to $296.9 million in the same period of 2025. Thursday’s results were largely driven by strong growth in its Managed Freight business, aided by the integration of its brokerage, improved pricing and lower purchased transportation costs.
The Chattanooga, Tenn.-based transportation company, which trades on the New York Stock Exchange under the ticker CVLG, said it earned $315.1 million in freight revenue excluding fuel surcharges, up 17.2 percent from $268.8 million a year ago.
The quarter also marked a significant improvement in profitability Net income was $10.7 million, or $0.40 per diluted share, compared with $9.1 million, or $0.35 per share, in the third quarter of 2025. Adjusted earnings per diluted share increased 13.6% from $0.44 to $0.50.
“This is the first time since the second quarter of 2022 that the company has had both sequential and year-over-year growth in adjusted earnings per share,” said Chairman and CEO David R. Parker.
Operating income was also higher at $12.5 million compared to $7.9 million a year earlier. But the adjusted operating ratio rose from 94.4% to 95%, which shows that the company’s financial efficiency was still impacted by the rising operating expenses.
Managed Freight is the key growth driver
Covenant’s Managed Freight division contributed the most to its quarterly performance. Revenues for this segment increased 68.4% to $121.6 million from $72.2 million for the third quarter of 2025.
The profitability improved even more markedly. Adjusted operating income increased 133.3% to approximately $7.08 million from $3.04 million. At the same time, the adjusted operating ratio improved to 94.2% from 95.8%.
Covenant attributed the gains mostly to the integration of brokerage operations it acquired in the fourth quarter of 2025. Higher customer rates and lower costs for purchased transportation also helped the segment’s performance.
The acquired brokerage operations had their best quarterly performance since joining Covenant, Parker said. The company’s existing brokerage business also benefited from its ability to source additional carrier capacity to accommodate overflow freight from its expedited operations.
Still, turning a profit is difficult. With more trucking capacity exiting the market, it’s becoming more difficult to find qualified carriers willing to accept below-contractual freight prices. “Higher insurance premiums and claims expenses are other risks for the division,” Covenant also said.
Smaller truckload fleet results in higher revenue per mile
Covenant’s Truckload operations had total revenue of $204.6 million for the quarter, up 2.5 percent from $199.7 million in the third quarter of last year.
However, freight revenue, excluding fuel surcharges, moved in the opposite direction, declining 3.4% to $166 million from $171.8 million.
The decline was mainly due to the company’s continued fleet rationalization strategy. Its average tractor fleet fell 8.9%, to 2,186 from 2,400 units.
Covenant saw significant improvements in revenue productivity and freight pricing, even with fewer tractors. Revenue per total mile increased 19.8% to $3.03 compared to $2.53 a year ago. Revenue per tractor per week also rose 6.1% to $5,778 from $5,445.
But average mileage per tractor dropped 11.4 percent to 25,081 miles from 28,306 miles.
President Paul Bunn said, “A better freight rate and a better mix of business helped offset the smaller fleet.” Still, inflation and costs associated with repositioning equipment and drivers weighed on operating performance.
Adjusted operating income in the Truckload division slipped to $7.9 million from $10 million and its adjusted operating ratio deteriorated to 95.3%, from 94.2% in the third quarter of 2025.
“Adjusted truckload operating expenses increased approximately 20.8% year over year, compared to the approximate 19.7% increase in freight revenue per total mile,” Bunn noted.
The company cited a number of reasons for the increase, including wages and benefits for employees, depreciation of equipment, maintenance, investments in technology and one-time costs associated with the initiation of new customer contracts.
Expedited operations concentrating on long-term capacity agreements
Covenant’s Expedited division also continued to restructure its operations around multiyear capacity commitments, operating a smaller fleet and placing more emphasis on contract business.
Freight revenue, excluding fuel surcharges, fell 12% to $70.6 million from $80.2 million in the same quarter of 2025. The average fleet of tractors fell sharply, down 21.4% to 677 units from 861.
Adjusted operating income was $4.16 million, down 19% from $5.14 million.
Despite these reductions, however, revenue productivity improved. Average freight revenue per tractor per week grew 12% to $7,934.
The transition to committed capacity agreements accelerated during the quarter. At the end of September, about 58% of Covenant’s Expedited tractors were operating under such agreements, up from about 40% at the end of the second quarter.
The Dedicated division also posted positive revenue growth. Freight revenue, excluding fuel surcharges, rose 4.2% to $95.4 million, compared with $91.6 million a year earlier. Revenue per tractor per week grew 6.2% to $4,810.
These gains were supported by the growth in transportation activity for agricultural protein products and the company’s decision to exit dedicated contracts that were less profitable.
Approximately 80% of tractors in its total asset-based fleet were on long-term agreements at the end of the third quarter.
Parker said Covenant plans to have substantially all of its asset-based operations under dedicated or other committed freight contracts by the end of the current freight market upcycle.
Steady freight demand faces ongoing cost inflation
“We had enough freight demand in most market segments and activity was particularly strong in sectors that are benefiting from the U.S. economic growth,” management said.
The operating environment, however, remains challenging. Transportation companies are feeling the squeeze from a shortage of drivers and rising employment costs.
Parker cited rising expenses for recruiting, retaining and paying drivers, as well as the increasing price tag for owning, maintaining and outfitting equipment with technology. “These pressures have eaten up so much of the financial benefit from better freight rates.”
Covenant believes that its growing use of firm capacity contracts will help reduce earnings volatility and improve profitability as market conditions further improve.
Its Warehousing division, however, had a tougher quarter from a profitability point of view.
Segment revenue rose 7.8% to $26.7 million, but adjusted operating income fell to $888,000 from about $2 million in the third quarter of 2025.
The company attributed the decline to inefficiencies at the new locations and higher labor costs.
Covenant expects Q4 earnings growth to continue
Looking ahead, Covenant expects adjusted earnings per share to increase modestly sequentially in the fourth quarter of 2026.
Management expects to continue shifting equipment to higher-margin committed contracts and to reduce costs associated with moving trucks and drivers.
The company also expects continued growth in its Dedicated fleet, while keeping its Expedited fleet relatively flat and pushing up the percentage of tractors operating under long-term agreements.
Covenant’s 49% ownership interest in Transport Enterprise Leasing generated $5.7 million in pretax income in the third quarter compared with $3.6 million a year ago. But the company expects that contribution to be lower in the fourth quarter.
Its financial position also improved somewhat. As at September 30, Covenant’s net indebtedness was approximately $283.9 million, a decrease of $12.4 million compared to the end of 2025. The company also had $75.2 million of borrowing capacity available immediately under its asset based lending facility.
Net capital expenditures for equipment are expected to be in the range of $35 million to $40 million for the balance of 2026.
Covenant Logistics: Key Q3 2026 financial indicators
| Financial and operational metric | Q3 2026 | Q3 2025 | Year-over-year change |
|---|---|---|---|
| Total revenue | $353.9M | $296.9M | +19.2% |
| Truckload total revenue | $204.6M | $199.7M | +2.5% |
| Freight revenue excluding fuel (companywide) | $315.1M | $268.8M | +17.2% |
| Truckload revenue per total mile | $3.03 | $2.53 | +19.8% |
| Truckload revenue per tractor per week | $5,778 | $5,445 | +6.1% |
| Managed Freight revenue | $121.6M | $72.2M | +68.4% |
| Managed Freight adjusted operating income | $7.08M | $3.04M | +133.3% |
| Expedited freight revenue excluding fuel | $70.6M | $80.2M | -12.0% |
| Expedited adjusted operating income | $4.16M | $5.14M | -19.0% |
| Adjusted earnings per share | $0.50 | $0.44 | +13.6% |
Source: Covenant Logistics Group, third-quarter 2026 financial and operating results.
Why it’s important: “The results from Covenant are indicative of how trucking operators are navigating a soft freight market through fleet reductions, improved contract pricing and a heightened focus on asset-light brokerage activities. We saw strong revenue growth in Managed Freight and a higher percentage of tractors under long-term contracts, which demonstrates the benefit of more predictable freight volumes while managing continued inflation in labor, equipment and operating costs.