Maritime Nov 3, 2026
Alternative-Fuel Vessel Orders Jump 57% as Port Infrastructure Struggles to Keep Pace
DNV reports 364 alternative-fuel vessel orders in the first ten months of 2026, driven largely by LNG-powered ships, while Lloyd’s Register warns that limited methanol and ammonia bunkering facilities could hinder the industry's transition.
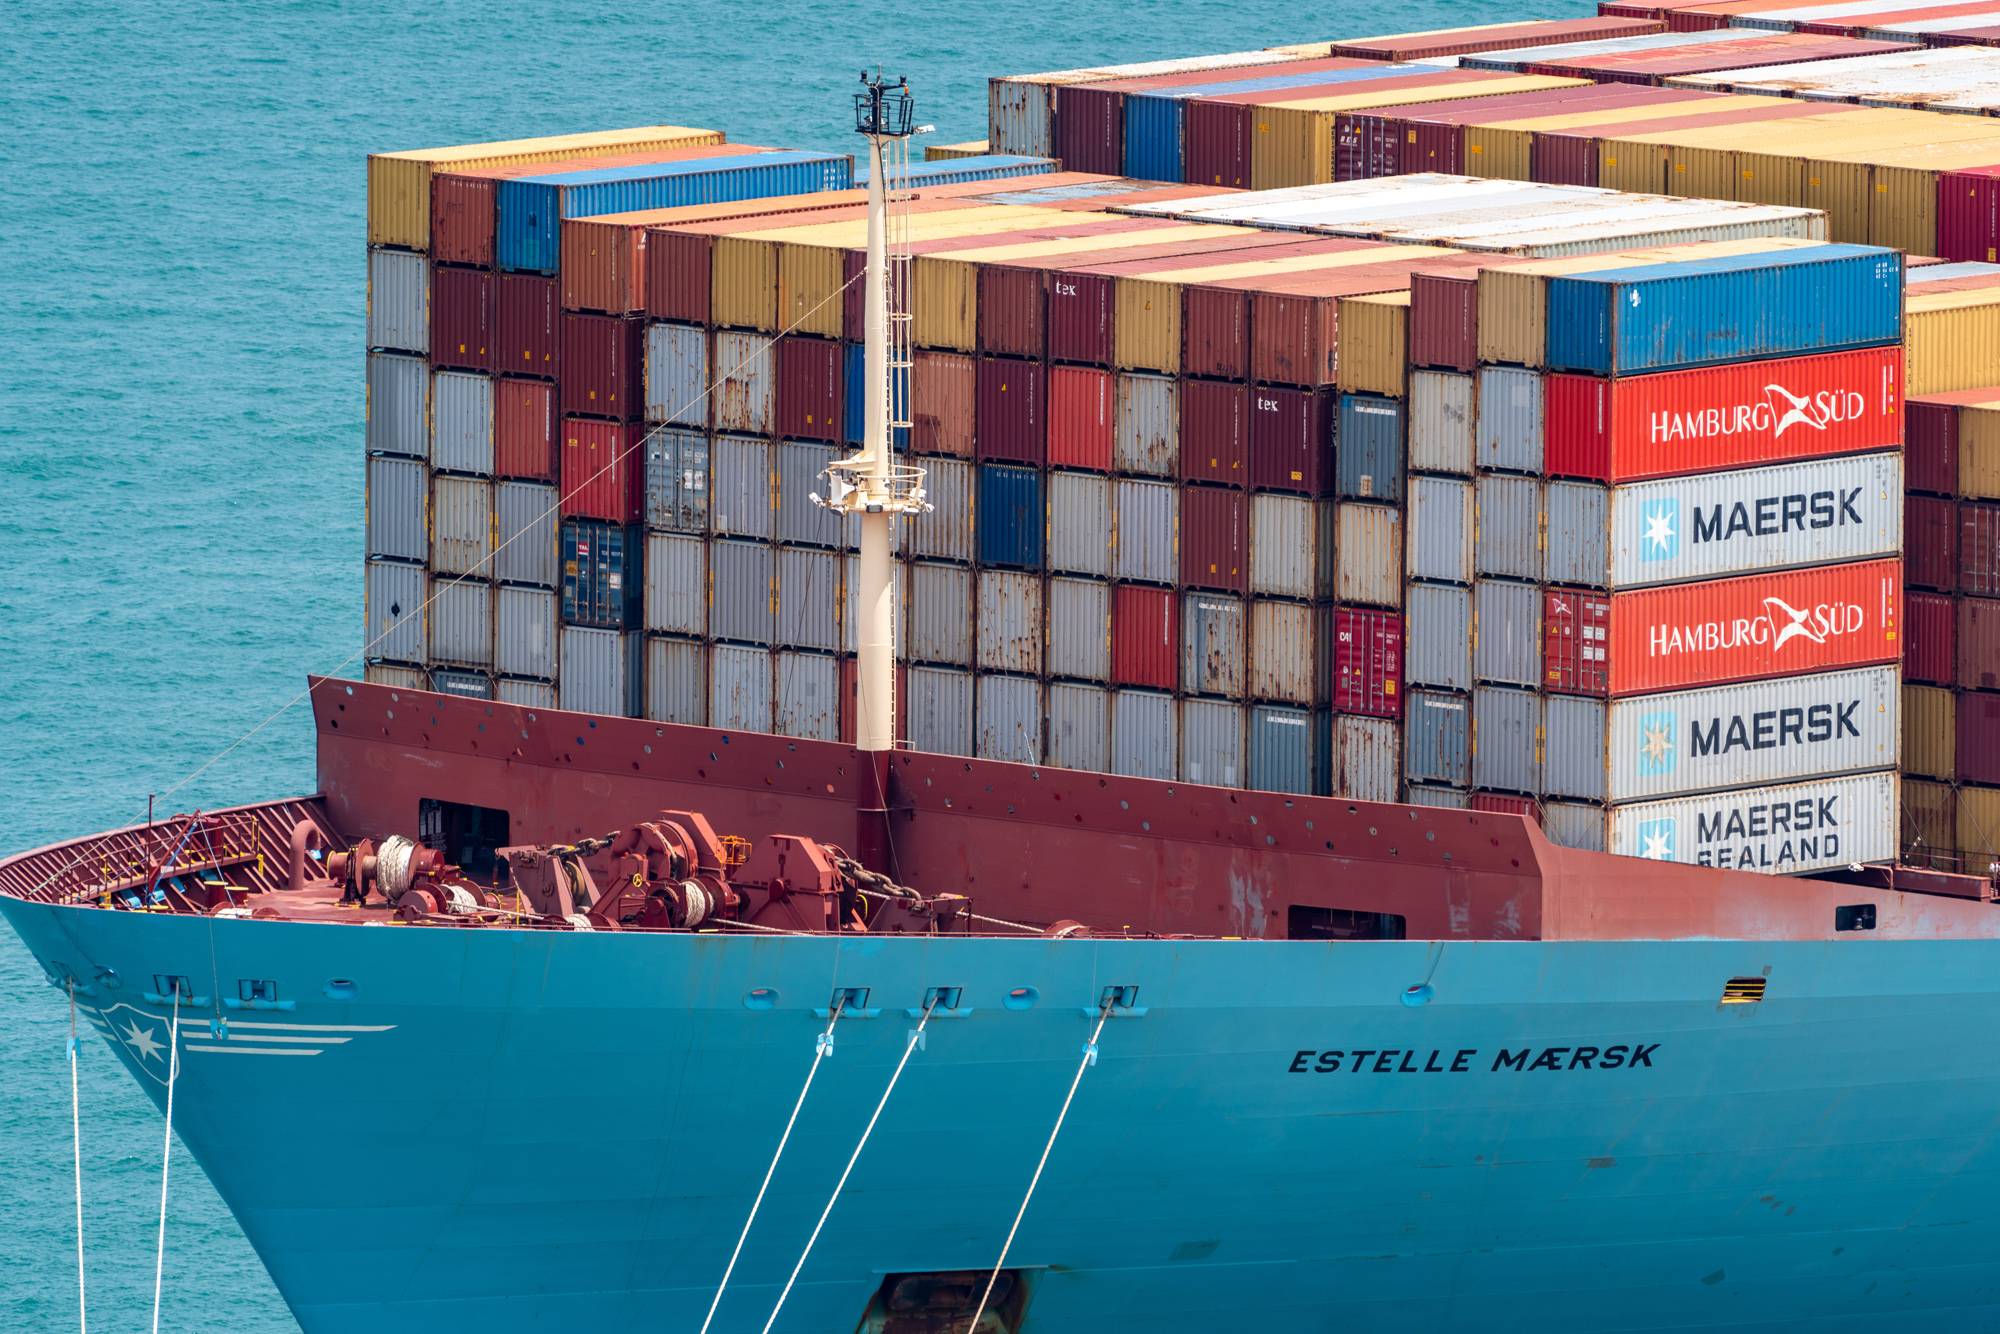
The global shipping industry is moving quickly into alternative fuels and new vessel orders keep growing in 2026. With the growth of the alternative-fuel fleet, a big challenge is becoming increasingly apparent: availability of port infrastructure capable of supplying these fuels.
Figures from DNV show 53 alternative-fuel vessels were ordered in October, taking the total number of contracts placed during the first ten months of the year to 364.
LNG-fueled vessels were a strong presence, taking up the majority of October’s orders. Of the 53 newbuilds, 30 were designed to run on liquefied natural gas (LNG) and 19 were powered by liquefied petroleum gas (LPG). The other four vessels were ammonia-fueled.
“October’s numbers continue to support the strong order intake we have seen since the summer,” said Global Decarbonization Director at DNV Maritime, Jason Stefanatos. In particular he pointed to the continuing concentration of LNG-fuelled vessel orders in the container and car carrier segments.
These two vessel types together account for nearly nine out of every ten LNG-fuelled orders in 2026. This trend illustrates how shipping sectors with close connections to consumer supply chains are leading the way in the adoption of alternative fuels.
LNG remains the dominant player in newbuilding orders
The figures since January further demonstrate the strength of LNG in the alternative-fuel vessel market. Of the 364 contracts reported for the first ten months of 2026, 230 were for LNG-fuelled vessels. There were 103 orders for LPG-powered ships.
The maturity of the LNG supply chain and bunkering infrastructure also contributes to its continued appeal, said DNV. LNG has practical advantages over many other alternative fuels due to the increasing fleet of bunker vessels and existing fuel supply networks.
The ability to support a transition to lower-carbon alternatives also gives operators greater flexibility in long-term investment decisions. This flexibility, Stefanatos said, is an important consideration throughout the operational life of a vessel.
Methanol and ammonia infrastructure still a major hurdle
However, the increase in orders for alternative-fuel vessels has not been matched by a widespread availability of adequate bunkering facilities in global ports.
A new study from fellow classification society Lloyd’s Register (LR) highlights the growing gap between the development of the fleet and the infrastructure required to service it.
The study shows that LNG is now available at 222 ports around the world. But the picture is far more limited for other alternative fuels.
LR identified 385 methanol-ready vessels and 45 ammonia-ready vessels on order. However, there are only 25 ports with methanol bunkering facilities today and only one port with commercial ammonia bunkering operations.
The figures call into question whether port infrastructure can be developed fast enough to accommodate the growing number of ships designed to operate on fuels other than LNG.
The development of the fleet was outstripping the infrastructure to support it, warned Kamran Ul Haq, senior vise president of LR Ports Advisory.
The order for a vessel powered by the alternative fuels is not a guaranty of the availability of the required fuel at the ports where the ship is anticipated to operate, he pointed out. Thus, fuel procurement strategies cannot be seen as separate from commercial trading strategies for shipowners.
Ports to make tough decisions on future fuel supply
The challenge for port authorities and infrastructure operators is not to necessarily invest in every alternative fuel available. LR instead argues that ports should locate where credible demand is likely to arise and plan for it.
This preparation will require putting in place the safety standards, regulations, technical skills and partnerships needed for future bunkering operations.
“Ports that anticipate these requirements and make strategic decisions early will be better positioned as alternative-fuel volumes increase,” says Ul Haq.
The latest figures thus show two contrasting developments in maritime decarbonization. Shipowners are increasingly committing to vessels powered by alternative fuels, but the infrastructure required to supply those vessels is at different stages of development.
The continued growth of LNG bunkering shows what a more developed alternative-fuel network can deliver. However, methanol and ammonia still have major infrastructure constraints that may affect their commercial uptake and future design of vessels to use them.
END OF REPORT