Cargo Nov 4, 2026
ArcBest exceeds third-quarter forecasts as heavier freight lifts revenue and tonnage
Higher shipment weights strengthen the LTL business, while the company projects a 91.4% operating ratio for the fourth quarter and sees further improvement ahead in 2027.
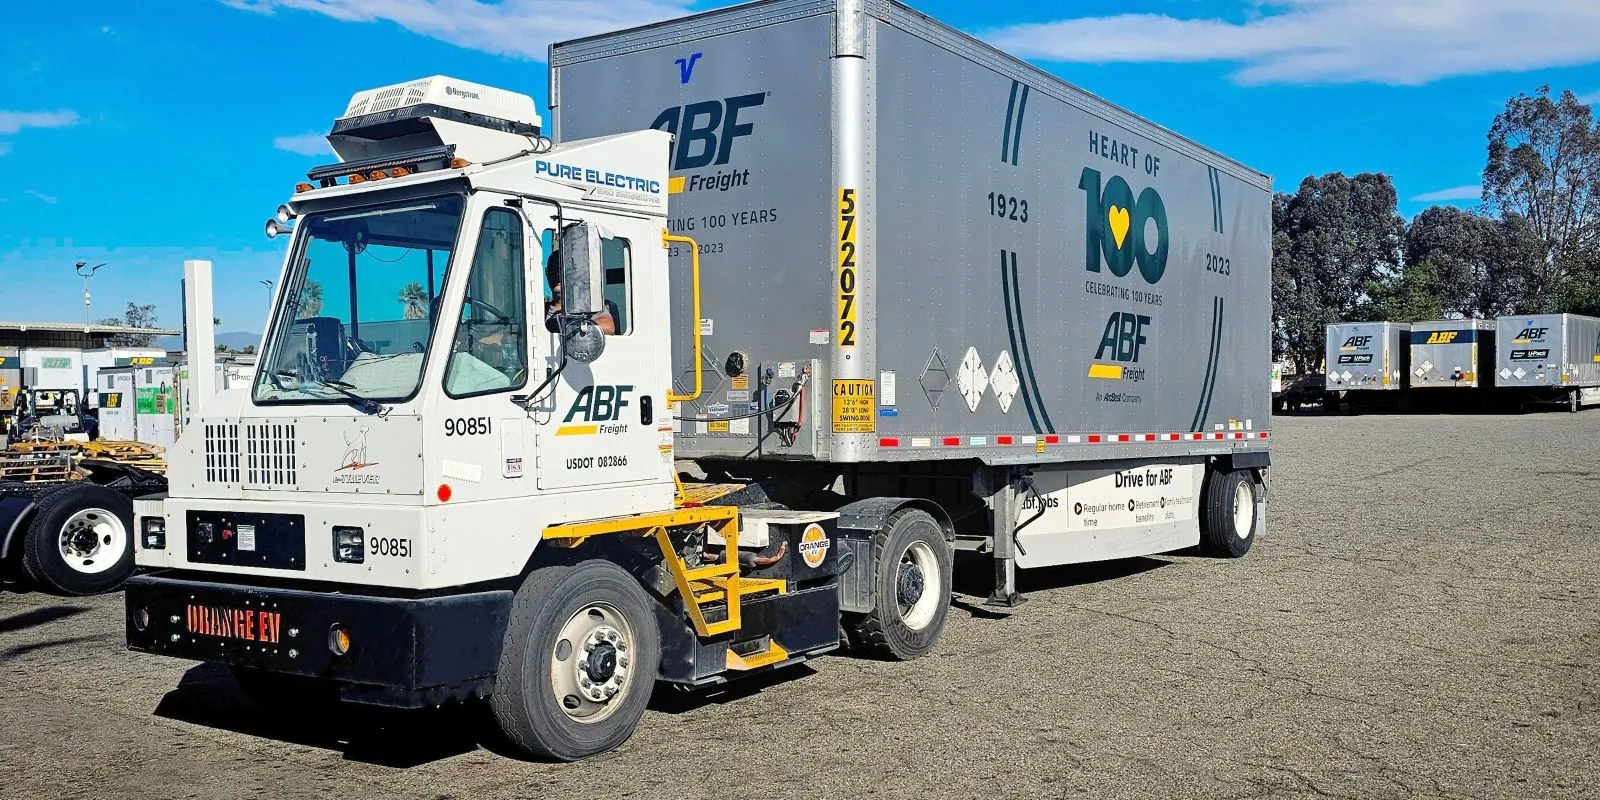
ArcBest delivered stronger-than-expected third-quarter results, supported by heavier freight shipments, increased tonnage and improved revenue per shipment across its less-than-truckload (LTL) operations.
The company benefited from a changing freight environment, as volumes previously diverted to the depressed truckload market began returning to the LTL network. Improving conditions in the manufacturing sector also contributed to the stronger performance.
The latest manufacturing data offered further encouragement. The Institute for Supply Management's Manufacturing Purchasing Managers' Index (PMI) reached 55.5 in October, remaining in expansion territory for the tenth consecutive month. The reading exceeded expectations by 100 basis points and was also 100 basis points above September's level. A PMI above 50 indicates expansion, while a reading below that threshold signals contraction.
Against this backdrop, ArcBest (NASDAQ: ARCB) announced adjusted earnings per share of $2.62 on Wednesday before the market opened. This represented an 80% increase compared with the same period last year and exceeded analysts' consensus estimate by 11 cents. The adjusted figure excluded restructuring expenses, technology costs and other nonrecurring items.
Consolidated revenue increased 15% year over year to $1.21 billion, matching market expectations.
Heavier shipments reshape ArcBest's LTL performance
ArcBest's asset-based segment, which includes its LTL subsidiary ABF Freight, generated $799 million in revenue during the third quarter, representing a 10% annual increase.
Tonnage also rose 10%, despite a 3% decline in shipment numbers. The difference was driven by a substantial increase in average shipment weight, which climbed 13% year over year.
The monthly figures illustrate the acceleration in freight volumes. Tonnage increased 8.1% in July, 9.1% in August and 11.6% in September compared with the corresponding months of the previous year.
Revenue per hundredweight, including fuel surcharges, improved by 1%, while revenue per shipment advanced 14%. Both indicators benefited from the heavier freight profile.
However, yield excluding fuel surcharges declined by a low-single-digit percentage. The increase in shipment weights, combined with a 2% reduction in average length of haul, placed additional pressure on this measure.
Contractual rate increases averaged 5.1% during the quarter, rising to 9.6% on a two-year-stacked comparison. ArcBest had previously introduced a 5.9% general rate increase across the LTL services of both its business units in June.
Operational efficiency also improved. The asset-based segment recorded an adjusted operating ratio of 90.4%, an improvement of 210 basis points compared with the third quarter of 2025. The figure was also 40 basis points better than the second quarter, outperforming management's earlier expectation of no significant sequential change.
On the insurance front, ArcBest reported lower base liability insurance premiums following a recent renewal, while maintaining its existing coverage limits. The company nevertheless retained greater exposure to risk on one of its excess insurance layers. Management noted that this particular coverage had been used only twice over the past 25 years.
Quarterly expenses also reflected the impact of the annual wage increase required under the company's union agreements.
ArcBest | Q3/26 | Q3/25 | Y/Y Gross Change | Y/Y % Change |
|---|---|---|---|---|
Asset-Based: | ||||
Revenue | $798.6 | $726.5 | $72.1 | 9.9% |
Workdays | 64.0 | 64.0 | 0.0 | 0.0% |
Revenue/Day | $12.5 | $11.4 | $1.1 | 9.9% |
Tonnage per Day (tons) | 12,313 | 11,238 | 1,075 | 9.6% |
Shipments per Day | 20,460 | 21,095 | -635 | -3.0% |
Revenue per Hundredweight | $50.75 | $50.19 | $0.56 | 1.1% |
Revenue per Shipment | $610.78 | $534.80 | $75.98 | 14.2% |
Pounds per Shipment | 1,204 | 1,065 | 139 | 13.1% |
Length of Haul (miles) | 1,112 | 1,129 | -17 | -1.5% |
Adjusted Operating Ratio | 90.4% | 92.5% | -210 bps | -2.3% |
Asset-Light: | ||||
Revenue | $446.3 | $356.0 | $90.3 | 25.4% |
Adjusted Operating Ratio | 96.8% | 99.6% | -280 bps | -2.8% |
Adjusted Operating Income | $14.4 | $1.6 | $12.8 | 803.9% |
Adjusted EBITDA | $15.6 | $3.1 | $12.5 | 410.9% |
Consolidated: | ||||
Revenue | $1,210.5 | $1,048.1 | $162.4 | 15.5% |
Adjusted Operating Ratio | 92.9% | 95.2% | -231 bps | -2.4% |
Adjusted EBITDA | $119.7 | $104.0 | $15.7 | 15.1% |
Adjusted EPS | $2.62 | $1.46 | $1.16 | 79.5% |
Revenue, operating income and EBITDA in millions
ArcBest's key performance indicators highlight the company's third-quarter operating and financial performance.
Fourth-quarter outlook points to a 91.4% operating ratio
Early fourth-quarter trends indicate that the asset-based business is maintaining its momentum.
In October, revenue per day increased 20% year over year, supported by a 15% rise in tonnage and a 4% improvement in yield. Shipments grew 1%, while revenue per shipment climbed 18%.
October tonnage was just 1% below September's level, compared with the typical sequential decline of approximately 3.4% for that period.
Yield excluding fuel remained lower by a low-single-digit percentage year over year, largely reflecting a 14% increase in average weight per shipment.
Management expects the growth in shipment weights to moderate as comparisons with the previous year become more challenging. To maintain network efficiency, ArcBest will continue relying on its dynamic quoting pool, a system designed to match available network capacity with transactional freight opportunities each day.
The company also expects a more limited deterioration in its operating ratio during the fourth quarter than is normally observed.
Historically, the asset-based segment's operating ratio worsens by approximately 180 basis points between the third and fourth quarters. This year, management anticipates a smaller deterioration of between 50 and 150 basis points.
At the midpoint of that forecast, the implied fourth-quarter operating ratio stands at 91.4%, representing a 480-basis-point improvement over the same period last year.
Looking further ahead, ArcBest expects 2027 to deliver another step forward toward achieving its previously announced financial targets for 2028.
Asset-light division surpasses upgraded third-quarter guidance
ArcBest's asset-light segment also performed better than anticipated, exceeding the higher expectations management had established in August.
The division, which includes the company's truck brokerage activities, generated adjusted operating income of $14.4 million in the third quarter. This was above the revised forecast of $10 million to $12 million.
The revised outlook had already represented an improvement on the initial guidance of $6 million to $8 million for the segment.
Revenue reached $446 million, increasing 25% year over year. Shipment volumes rose 1%, while revenue per shipment surged 24%, including fuel-related charges.
Purchased transportation expenses, measured as a percentage of revenue, increased by 10 basis points year over year to 85%. At the same time, operational productivity improved, with shipments per employee per day increasing 8%.
Selling, general and administrative expenses also declined by 2%, providing additional support to the division's profitability.
The positive trend continued into October. Revenue per day was 27% higher than a year earlier, with shipments increasing 8% and yield improving 18%.
For the fourth quarter, ArcBest expects adjusted operating income from its asset-light operations to range between $7 million and $10 million.
Results offer insight into the wider LTL market
ArcBest's latest performance provides an important indication of conditions across the less-than-truckload industry, where the number of publicly traded operators remains relatively limited.
Its quarterly figures therefore offer valuable insight into a segment of the trucking market for which publicly available operating data are relatively scarce.
The company's results highlight how shipment composition, freight density, manufacturing activity and network capacity management can influence revenue and profitability, even when shipment counts remain under pressure.
ArcBest is scheduled to hold a conference call at 9 a.m. Eastern Standard Time on Wednesday to discuss its third-quarter results in greater detail.
END OF REPORT