Land Nov 5, 2026
North American Class 8 truck orders fall 36% as regulatory uncertainty weighs on fleets
October orders dropped to 15,600 units, nearly half the decade average, as carriers reassess their investment priorities amid uncertainty surrounding EPA emissions rules, rising equipment prices and mounting operating costs.
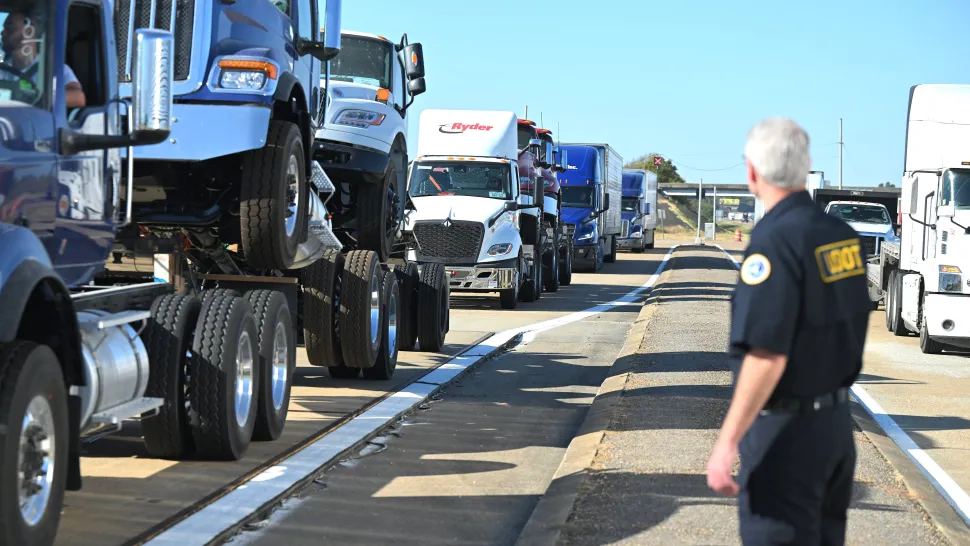
North America’s heavy-duty truck market is beginning to show signs of slowing as fleets become more cautious about purchasing new equipment. October saw a 36% year-over-year decline in class 8 truck orders, a weak start to the 2027 ordering season.
The slump comes amid uncertainty for trucking companies about upcoming emissions rules, higher equipment costs and continued pressure on operating margins. These challenges are forcing carriers to rethink how they invest, figures released Wednesday by FTR Transportation Intelligence show.
“We are hearing that some fleets are moving their capital spend to trailers instead of tractors in the near term,” said Dan Moyer, FTR’s senior analyst for commercial vehicles. While freight rates have improved, operating expenses are rising, making decisions on purchases more complicated.
"Also, while freight rates are strong, so are costs for fuel, insurance and labor, pressuring margins and possibly limiting purchases for now," Moyer said.
Preliminary net orders were 15,600 units in October, down 24% on September. The number is also nearly 50% off the 10-year monthly average of 31,089 units, indicating the extent to which heavy-duty truck demand has slowed as the industry moves toward 2027.
Overall though the bigger picture looks more positive when you look at activity since the start of the year. Cumulative Class 8 orders through October were 278,201 units, up 74% versus the same period in 2025.
Total order volume for September and October stood at 36,002 units. Despite the strong year-to-date performance, the two-month total was 20% below the same period a year earlier, FTR reported.
EPA prebuy effect is fading
FTR sees several underlying market conditions that still support demand, including the need to replace aging equipment, tighter trucking capacity and firmer freight rates.
However, the buying enthusiasm from fleets looking to purchase trucks ahead of the expected 2027 emissions rules appears to have mostly played out.
“We are entering a different phase now,” said Moyer, “where buying decisions will be more and more based on carrier financial performance, investment priorities and a greater clarity on regulatory requirements.”
“Underlying replacement needs, tighter capacity and firmer freight rates continue to underpin Class 8 demand,” Moyer said. “But with the earlier EPA 2027 pre-buy now over, orders are increasingly tied to fleet profitability, capital spending priorities and regulatory certainty.
Delayed purchases could help a subsequent recovery
Although the October numbers were disappointing, FTR cautioned that the decline should not be read as a definitive cancelation of fleet investment. Some carriers may simply be waiting to make purchasing decisions until they have a better sense of future emissions rules, manufacturing schedules and equipment prices.
That leaves the door open for an orders rebound as uncertainty fades and fleets feel more comfortable putting capital to work on new trucks.
“The weak October results suggest some purchases might be deferred and not cancelled and orders could strengthen as emissions requirements, production schedules and equipment pricing become clearer,” Moyer said.
But the slow start to the 2027 ordering season raises questions about equipment demand down the road and how truck makers will adapt their production plans. Replacement needs and higher freight rates continue to be supportive factors, but the pace of new orders will increasingly depend on fleet profitability and the regulatory outlook.
END OF REPORT