Maritime Nov 19, 2026
Zim Leverages Network Flexibility to Strengthen Profitability and Expand Pacific Operations
The Israeli container carrier attributes its strong financial performance to a strategy focused on high-yield trade routes, operational agility and disciplined capacity allocation, while preparing to introduce a third China–US West Coast service.
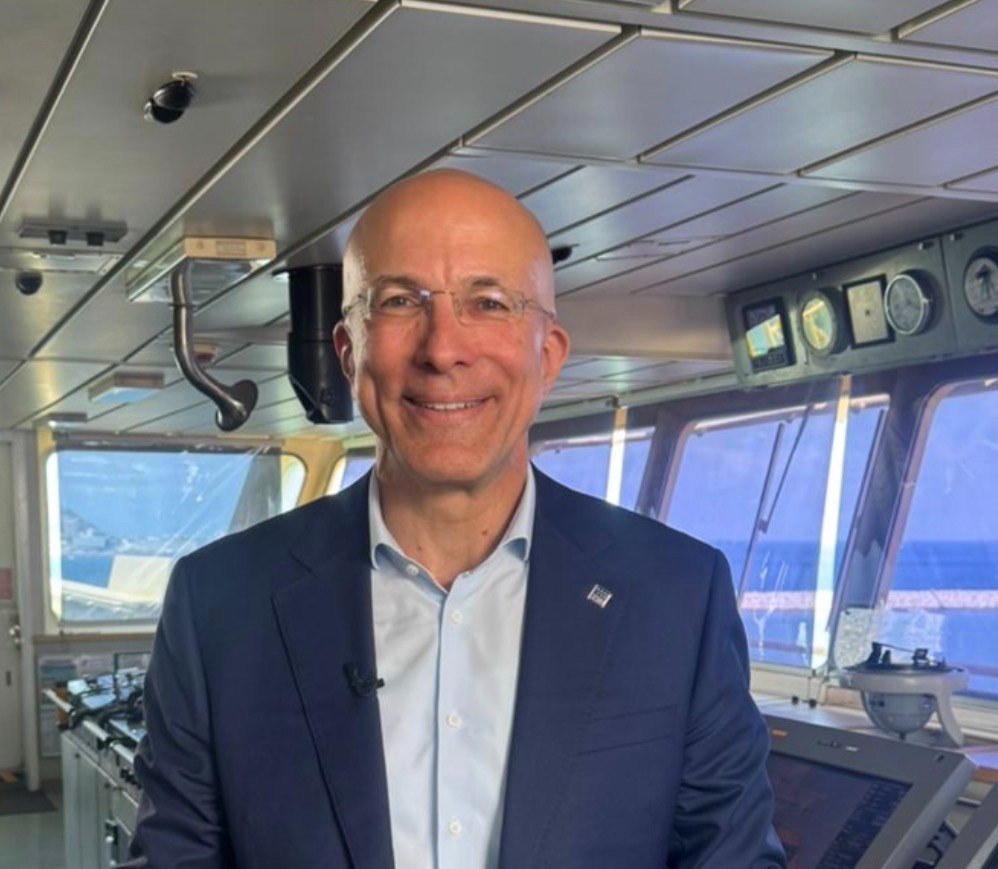
Zim is leveraging the flexibility of its global shipping network to improve profitability by focusing on high-performing trade routes and shifting resources to the most attractive market opportunities. Chen Lichtenstein, president and CEO, said this strategy had been behind the Israeli container carrier’s recent financial performance.
The effect of this approach is reflected in the company’s results for the third quarter of 2026. Revenue rose 53% to $2.71 billion and net income jumped 573% to $830 million, compared with $123 million in the third quarter of 2025.
“The surge in freight rates was a key driver for this performance. Zim averaged $2,480 per TEU for the quarter, up 55% year-on-year. This was more than $500 per TEU higher than its nearest rival, HMM. The carrier handled 962,000 TEU during the period, an increase of 4% compared with previous year.
“The company’s ability to maintain a flexible network and focus on premium profitable trades is enabling it to support customers and prepare for further growth,” Lichtenstein said. Since starting in the role on 1 July he has placed a real emphasis on driving market opportunities through proactive resource allocation.
The CEO also pointed out the company’s strategy for voyage management, where every sailing is optimized for better profitability and operational details are closely monitored.
“The latest figures are a testament to Zim’s differentiated business model and our established position in key shipping markets, notably the transpacific, and our ability to quickly respond to changing market conditions,” said Lichtenstein.
Year-to-date performance driven by third quarter results
Zim’s solid third quarter results have helped its overall performance. The financial numbers for the first nine months of 2026 are as follows:
Revenue for the January to September period rose 9% year on year to $5.8 billion. The growth came despite loaded container volumes falling 1% to 2.75 million TEU.
Average freight rate was $1,813 per teu. Nine-month net profit hit $808 million. However, it is still around $200 per TEU higher than CMA CGM’s reported average of $1,614, though this is below the third quarter average.
The carrier also expects to see its fleet-related expenses improve. It expects its vessel costs to decline by as much as 30% by 2027, helped in part by charter contracts built around falling rates. The company did not say, however, how many vessels were on declining-rate contracts versus those covered by fixed-rate agreements.
Zim’s strategy is centered on the Pacific routes
Zim continues to market itself as a leading operator on lucrative Pacific trade lanes, especially with its express services. The company is seventh in the market for its non-express loops and claims fourth place on the US East Coast services.
However the precise extent of the latter ranking is uncertain, including whether it covers both Atlantic loops and services connecting Asia with the US via the Panama Canal.
The Pacific is still the company’s biggest revenue source, making up about 50% of its total revenue. Another 10% of operations are within Asia, while Latin America, the Atlantic and the trade routes Zim terms ‘Cross Suez’ each account for around 8%.
The company also confirmed that it does not operate in the Bab el-Mandeb Strait and Red Sea route, except as a slot charterer on services operated by other carriers.
Third China-US West Coast service to be launched
Zim is building on its Pacific footprint with a third transpacific service connecting China with the US West Coast.
Lichtenstein confirmed the company is preparing to launch the ZX3 service calling at Xiamen, Shanghai and Los Angeles. This will complement the existing ZX2 service between Los Angeles and Shanghai.
Zim’s ZEX service will continue to connect ports in southern China with the US West Coast, further cementing its footprint in the region.
The carrier is also starting its Falcon service connecting China with Argentina and Brazil outside the transpacific market. The new route will reinforce its coverage of the Latin American market.
Fleet capacity and charter commitments are being considered.
Zim currently operates a fleet of 112 container ships with a combined capacity of 703,000 TEU and 13 car carriers. That compares with 116 container vessels with a total capacity of 711,000 TEU and 14 car carriers in the fleet last year.
About half of its container fleet is made up of vessels ordered by shipowners for charter to Zim. This is equivalent to 56 vessels with a total capacity of approximately 418,000 TEU. The company has four more car carriers on order under similar agreements.
Another key factor in the company’s fleet planning for the next two years will be the expiration of charter contracts.
Seven chartered vessels with a total capacity of around 22,000 TEU are expected to end their contracts this year. Another 14 vessels with a combined capacity of about 26,000 TEU are due to expire next year.
In either case, Zim can either return the vessels to their owners or extend the current charter agreements.
Managing these commitments, and adjusting its fleet deployment to changing market conditions, will continue to be an important element of its strategy. The flexibility, as well as the expansion on Pacific and Latin American routes, is key to Zim’s efforts to remain profitable and strengthen its competitive position in the global container shipping market.
END OF REPORT