

Container lines are gradually restoring capacity through the Suez Canal and southern Red Sea, even as the Houthi threat along the route continues to expand. The shift is putting downward pressure on Asia-Europe spot rates, but it also leaves carriers and cargo owners exposed should disruption return to one of the world’s most important shipping corridors.
The Iran-backed Houthi movement has recently taken control of a strategic port and an island directly on the Bab el-Mandeb Strait at the southern entrance to the Red Sea, according to analyst and data provider Freightos (NASDAQ: CRGO) in a research note. The territorial advance came shortly after an attack last week on a key Saudi oil pipeline, increasing concerns that further regional escalation could put additional pressure on oil and marine-fuel markets.
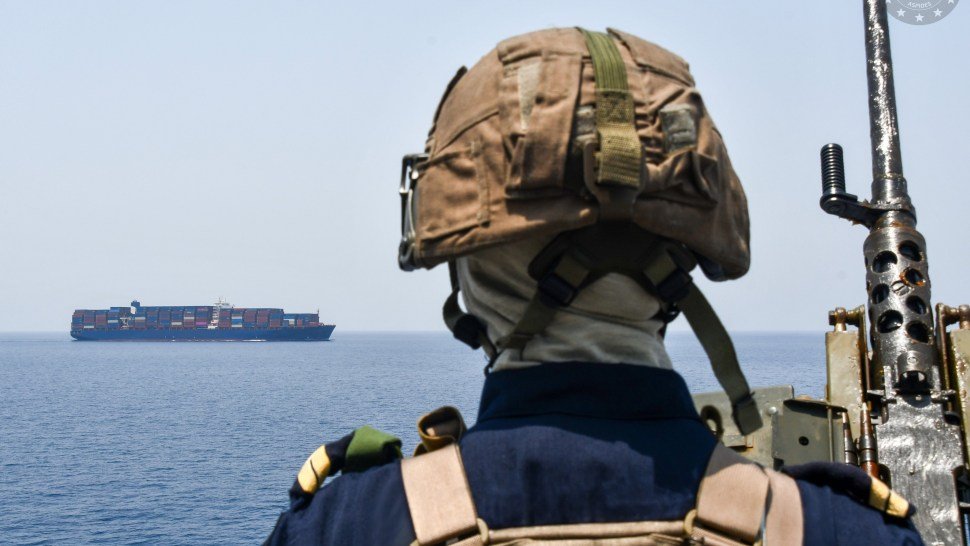
The Yemen-based terrorist militia had already shown that it could attack or deter merchant vessels operating in the Red Sea before securing additional coastal territory. Its latest advance, however, strengthens its position close to one of global shipping’s most critical chokepoints, connecting the Red Sea with the Gulf of Aden and forming the southern gateway to the Suez Canal.
The development comes as some observers question whether measures previously used to limit energy-price shocks during the conflict — including releases from strategic reserves — are becoming less effective. Oil and bunker fuel prices have climbed back toward May levels, raising concerns that another disruption could trigger a sharper fuel-market crisis.
Red Sea capacity returns
Despite resistance from some shippers and the increased security risk, carriers are putting more capacity back through the Red Sea and Suez Canal, with the most notable restoration taking place on Asia-Mediterranean services.
Sea Intelligence estimates that more than one-quarter of Asia-Europe capacity will use the Red Sea in September. The return has been particularly visible on the Asia-Mediterranean trade, where approximately 35% of headhaul capacity and between 50% and 60% of backhaul capacity are expected to transit Suez.
The recovery is moving at a slower pace on Asia-North Europe services. According to the estimates, around 6% of headhaul capacity and 30% of backhaul capacity had returned to the route.
The change is important because sailing through Suez significantly shortens voyages compared with routing vessels around Africa. A shorter transit can increase effective vessel capacity, reduce the number of ships needed to maintain weekly services and relieve schedule pressure — assuming the security environment remains stable.
Analysts estimate that as much as 2 million container units of capacity could return to the Mideast trade lane.
Asia-Europe spot rates fall
The growing use of the Red Sea route, combined with softer demand following the peak shipping season, appears to be putting pressure on Asia-Europe container rates.
Asia-North Europe spot prices declined 3% last week to approximately $4,300 per forty-foot equivalent unit (FEU). Asia-Mediterranean rates fell 12% to about $4,200 per FEU. Daily pricing on both routes had eased to roughly $3,800 per FEU so far this week.
The larger decline on the Mediterranean trade may be linked to the greater restoration of Red Sea capacity on that corridor. Asia-Mediterranean rates are now about $3,000 per FEU below their July peak, compared with a decline of roughly $2,000 per FEU for Asia-North Europe.
Rates, however, remain well above historical levels. Asia-North Europe pricing is still more than 20% above pre-peak-season levels recorded in mid-May, while Asia-Mediterranean rates remain more than 50% higher, according to the market update.
That resilience indicates that operational constraints have not disappeared despite the return of some Suez routings. Higher war-related fuel costs and congestion at Far East loading ports continue to disrupt schedules. Poor on-time performance and shipment backlogs could also remain an issue following China’s Golden Week holiday and extending into October.
Congestion at major North European hubs could also be affecting carriers’ decisions to restore Red Sea services. The shorter route allows shipping lines to recover schedule time and use their fleets more efficiently, even while terminals and inland transportation networks remain under pressure.
Trans-Pacific rates remain firm
Across the trans-Pacific, spot rates edged higher last week and continue to sit close to peak-season levels.
Strong import demand, combined with congestion in Asia, is continuing to support pricing. However, the latest National Retail Federation outlook forecasts that U.S. ocean import arrivals will fall 9% in October compared with September, followed by another decline in November. The projection suggests that cargo demand may already be starting to weaken.
A reduction in demand by itself may not be enough to trigger a rapid fall in freight rates. Continued port congestion and carrier blank sailings during the holiday period could restrict available capacity sufficiently to keep prices relatively high even if cargo volumes decline.
Most carriers do not appear to be preparing broad October general rate increases. CMA CGM, however, has announced significant peak-season surcharges, particularly on South Asia-to-U.S. trades.
Why it matters
Carriers are recovering access to the shorter Suez route at precisely the moment when the route’s southern gateway is becoming more vulnerable. The restoration is helping reduce Asia-Europe freight rates and improve vessel utilization, but the expanding Houthi position around the Bab el-Mandeb means that carriers and cargo owners remain exposed to another potential disruption.