

Unfilled orders at U.S. manufacturers continued to climb in August, highlighting the growing pressure on industrial production as transportation costs, steel prices and supply chain uncertainty weigh on businesses. The backlog of outstanding factory orders increased 0.6% to $1,609.6 billion, according to the U.S. Census Bureau’s October 2 report on manufacturers’ shipments, inventories and orders.
The latest increase marks the 25th monthly rise in the past 26 months. Transportation equipment remained the largest contributor, accounting for $1,009.9 billion of outstanding orders and leading the increase recorded in August.
Despite the growing backlog, manufacturers made little progress in shipping goods. Shipments remained virtually unchanged at $658.6 billion, ending a run of eight consecutive monthly increases. New orders edged up 0.1% to $663.5 billion, while the ratio of unfilled orders to shipments increased to 6.87, compared with 6.81 in July. The Census Bureau does not adjust these figures for inflation.
Performance varied across manufacturing segments. Orders for motor vehicle bodies, parts and trailers increased 0.8%, while machinery orders advanced 1.1%. Nondefense capital goods orders, excluding aircraft, rose 1.6%.
Durable goods orders, however, declined 0.1%. Transportation equipment orders fell 0.7%, while orders for nondefense aircraft and associated parts dropped 4.3%.
Labor constraints and material shortages are adding to the difficulty of meeting demand. A respondent from the fabricated metal products industry told the Institute for Supply Management (ISM) that orders through the end of the year had exceeded forecast levels.
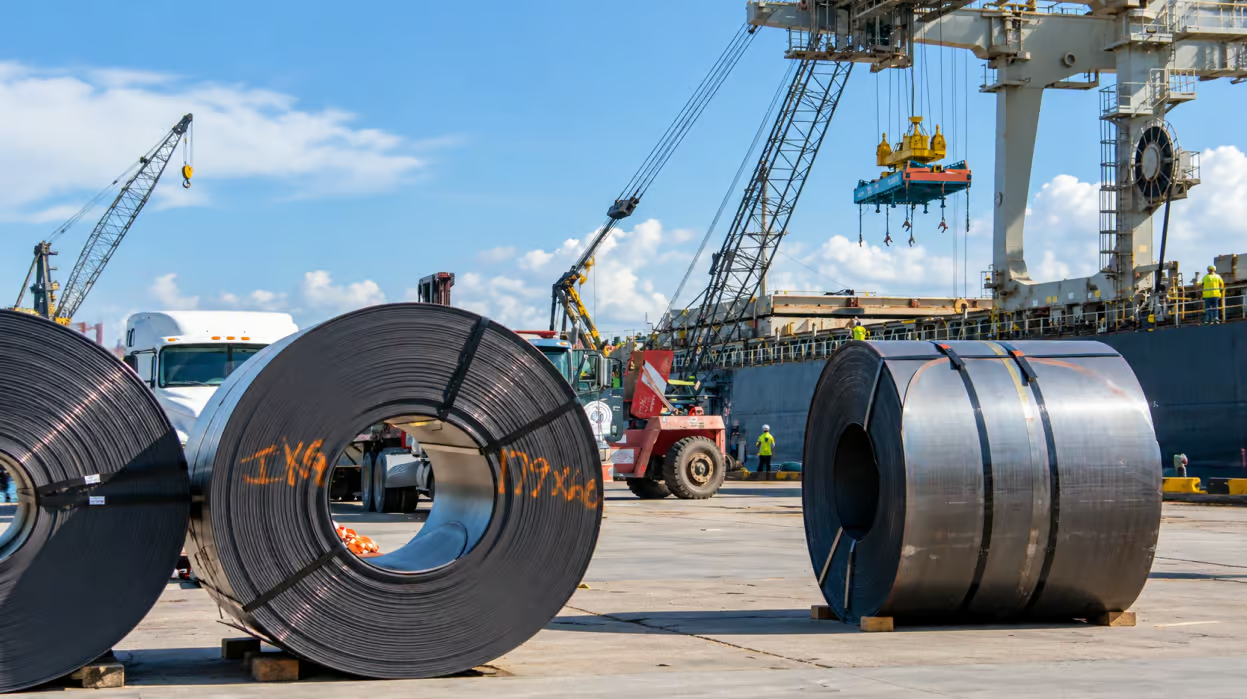
The company identified a severe shortage of workers as its main obstacle to increasing output. Limited staffing is restricting production capacity even as customer demand remains strong. Steel availability is another growing concern, with the respondent warning that market conditions are deteriorating and that additional production delays are likely as companies struggle to secure the materials they need.
Rising freight, diesel and steel prices squeeze manufacturers
The pressure on production is unfolding alongside persistently high input costs. ISM’s manufacturing Purchasing Managers’ Index registered 54.5 in September, down 0.1 point from August, according to the organization’s October 1 report. The reading marked the ninth consecutive month of manufacturing expansion following a 10-month contraction.
However, the prices component rose sharply. ISM’s Prices Index climbed 6.8 points to 77.9, the largest increase reported across the index’s components. The proportion of respondents reporting higher prices reached 58.6%, up from 46.2% in August.
Freight appeared among the commodities reporting price increases for the seventh consecutive month, while diesel fuel recorded its second consecutive month on the list. No commodities were reported as declining in price.
Fuel costs have become a particularly significant concern for transportation-dependent businesses. The U.S. Energy Information Administration’s weekly benchmark diesel price, widely used to calculate fuel surcharges, reached a record $6.529 per gallon on September 21, according to FreightWaves reporter John Kingston.
Susan Spence, chair of ISM’s Manufacturing Business Survey Committee, attributed the elevated prices index to three main factors: increases in steel and aluminum prices affecting the entire value chain, tariffs imposed on numerous imported goods, and higher prices for petroleum-based products linked to the conflict in the Middle East.
Industry feedback illustrates how these pressures are spreading beyond factory floors and into transportation budgets and procurement decisions.
A respondent from the food, beverage and tobacco products sector told ISM that fuel expenses continued to affect transportation costs and the overall cost of goods. A machinery industry respondent, meanwhile, reported that higher interest rates were slowing new construction activity. The company also faced increased costs for overseas components as tariffs and freight rates pushed expenses higher.
Manufacturers are also managing inventories that suggest continued supply chain strain. ISM’s inventories index fell two points to 48.6 in September, returning to contraction territory. The customers’ inventories index slipped to 41.6, marking its 24th consecutive month in the range considered “too low.”
Spence noted that a “too low” reading for the customers’ inventories index is generally viewed as a positive signal for future production. Nevertheless, the combination of constrained inventories and elevated input costs leaves manufacturers exposed to further disruptions if supplies become harder to obtain or demand increases unexpectedly.
Canada’s retaliatory tariffs add uncertainty to cross-border supply chains
Trade tensions with Canada are creating another source of uncertainty for manufacturers and logistics operators. August trade figures, released before Ottawa introduced its latest retaliatory measures, showed the U.S. goods trade deficit with Canada widening by $4.1 billion to $7.1 billion.
Imports from Canada increased by $4.6 billion to $37.1 billion, according to the Census Bureau and Bureau of Economic Analysis. On September 8, Canada imposed retaliatory tariffs ranging from 15% to 50% on approximately C$27.6 billion worth of U.S. goods. FreightWaves reporter Noi Mahoney reported that the measures followed the breakdown of negotiations in August and were intended to match U.S. duties.
The new tariffs are adding complexity to supply chains built over several years. A machinery industry respondent told ISM that the measures had increased cross-border costs and forced the company’s supply chain team to scramble to adjust established arrangements.
The respondent warned that these disruptions were undermining the very lead times that government buyers were seeking to protect. Orders and delivery times for semiconductors, electronics and government-related work had both doubled, according to the company.
The August trade figures also revealed a substantial increase in overall U.S. imports. Goods imports rose by $17.2 billion to $342.2 billion, while the goods trade deficit widened by $12.8 billion to $136.6 billion.
Industrial supplies accounted for $9.1 billion of the monthly increase in imports. Within that category, crude oil imports rose by $3.3 billion and nonmonetary gold imports increased by $3.1 billion. Capital goods imports advanced by $6.2 billion, including increases of $2.4 billion in semiconductors and $1.3 billion in other industrial machinery.
After adjusting for inflation using 2017 dollars, real goods imports increased 4.1% to $267.7 billion, compared with the 5.4% increase in nominal imports.
Despite the monthly deterioration, the broader trade balance showed a different trend. The U.S. goods and services deficit for the year to date was down 19.9% compared with the same period in 2025, while total imports had increased 4.4%.
Businesses delay investment as costs and demand remain uncertain
The trade conflict is also beginning to affect companies’ willingness to invest. The trade war with Canada was escalating, driving up prices and creating uncertainty that was significantly disrupting business activity, a respondent in the transportation equipment sector told ISM.
The company said customers were unwilling to commit to capital spending until they had a better visibility of future costs and demand and were continuing to push out purchases indefinitely.
Another obstacle for manufacturers already battling large order backlogs, a shortage of workers, rising steel prices and expensive shipping is that pause. The ongoing build-up of unfilled orders points to strong underlying demand, but the slow pace of shipments suggests manufacturers are not turning that demand into shipments at the same pace.
It is a tough operating environment for logistics providers, industrial suppliers and transportation operators, who are facing the challenges of higher freight and fuel costs, trade restrictions and postponed investment decisions. The path of production and shipping activity will depend not only on the strength of customer orders but on whether manufacturers can get materials, control costs and regain enough certainty to move goods and approve new spending.