

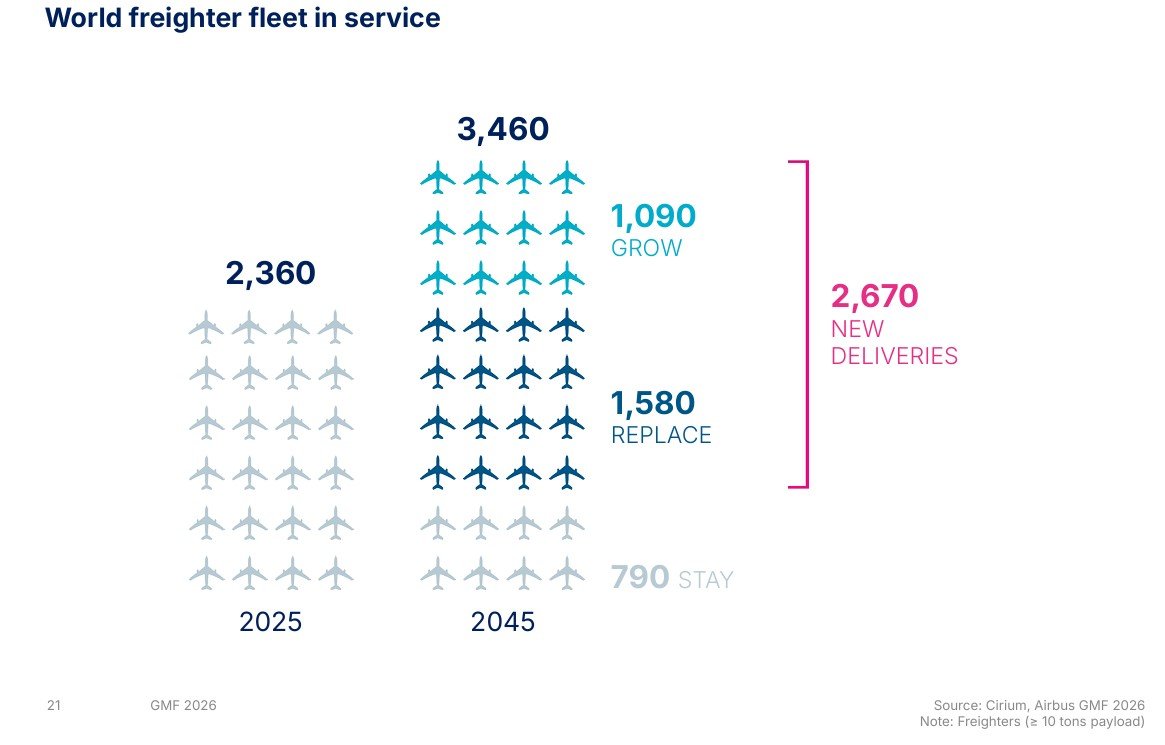
Airbus sees a significant growth in the global freighter fleet over the next 20 years fueled by continued demand for air freight transportation and the need to replace an aging aircraft fleet. In its latest long-term market outlook, the European manufacturer predicts 46% more freighters by 2045, a requirement of 2,670 additional aircraft, which is 65 more than it predicted in its last report.
The revised forecast, unveiled on Wednesday, contains only slight changes from Airbus’ earlier forecasts. The company has reduced its forecast for annual air cargo growth to 3.2% from 3.3% and raised its outlook for future aircraft needs.
Of the 2,670 aircraft expected to enter service, 970 will be newly-built freighters and some 1,700 will be passenger aircraft converted for cargo work. Of these, about 1,100 will be for market expansion and the rest for replacement of older aircraft.
Airbus’ previous forecast assumed 45% growth for the global freighter fleet based on 2,605 new and 815 existing aircraft. The 2026 outlook projects a total fleet of 3,460 aircraft, some 40 more than the previous estimate.
The demand projection indicates that 57% will be for medium and large wide-body freighters, highlighting the significance of aircraft capable of handling long-haul and intercontinental cargo operations.
Growth of air cargo outpaces global trade growth
Airbus’ forecasts are partly based on the expectation that global trade will continue to expand at an annual rate of approximately 2.9%. Historically, air cargo demand has outperformed international trade growth, despite geopolitical tensions, volatile fuel prices and supply chain disruptions.
The projected 3.2% annual growth rate is also higher than the average of 2.3% over the past two decades, which included two major global economic shocks.
The tariffs have not had an overwhelming impact on the demand for air cargo, leading to a more stable outlook than some market observers had predicted. Instead of causing a widespread contraction, trade restrictions have diverted shipments to other markets and altered established freight flows.
Asia is expected to continue to be the fastest growing regional market, with a 4% annual growth in demand for air cargo. The concentration of industrial manufacturing, electronics production and high-technology supply chains continues to underpin demand for air freight capacity.
Boeing expects an even stronger expansion
Airbus’ estimates differ from Boeing’s estimates released last year. The US manufacturer predicted a 67% increase in the global fleet, with 955 new aircraft, 2,900 additional freighters. Boeing also forecast annual growth in air cargo traffic at 3.7%.
The company will issue an updated market forecast next week, which may offer a fresh comparison of the long-term expectations of the two manufacturers.
Recent cargo traffic figures also show continued momentum. Global air cargo volumes rose 4.6% year on year through August 2026, according to the International Air Transport Association (IATA) and other market analysts.
That is an acceleration from the 3.3% growth registered in 2025 despite major obstacles to international trade, notably the imposition by the US administration of broad tariffs on trading partners, including China.
Trade barriers reshape global airfreight flows
US tariffs on Chinese goods, including large volumes of direct-to-consumer e-commerce shipments that had previously entered the United States duty-free, have led to a major redistribution of international trade.
Since last year, Chinese exports worth some $750 billion and the associated air cargo volumes have been rerouted to other markets. Meanwhile, the US has increased imports from alternative sources by $375 billion, mainly from Vietnam, Taiwan and Thailand. The extra imports have more than compensated for the fall in purchases from China.
Accenture’s global trade data shows US imports from the rest of the world are up 12% so far in 2026.
North American air cargo demand dropped 1.1% last year but has since rebounded. Chinese exports to the US have begun to recover on the back of tariff exemptions and other factors, pushing regional air cargo volumes up 5.9% year on year.
The Middle East is a different situation with air cargo volumes falling 6.5% in the first eight months of 2026 due to the US war with Iran. The region’s share of connecting cargo traffic fell to 31% from 38% during the same period last year.
Airlines have increasingly been re-routing their networks to avoid the affected region. Traffic between Europe and Asia grew 3% over the period as more and more carriers offered direct services between the two markets. The traffic of freighters has increased at Central Asian transit hubs like Baku in Azerbaijan and Tashkent in Uzbekistan.
AI infrastructure powers high-value cargo demand
The expansion of artificial intelligence infrastructure has also been a key driver of airfreight demand. Computers, semiconductors and electronic equipment now account for 15% of the total value of air cargo – about double their share two years ago.
A lot of this growth is fueled by hyperscale tech companies buying servers and associated gear to build and grow data centers.
The volume of these shipments has increased significantly but their share of cargo weight remains relatively small. High-technology goods represent 6.2% of air cargo weight, an increase of just 2.2 percentage points.
The figures illustrate the effect on air freight markets of investment in AI infrastructure without a corresponding increase in physical weight moved.
An ageing fleet drives replacement demand
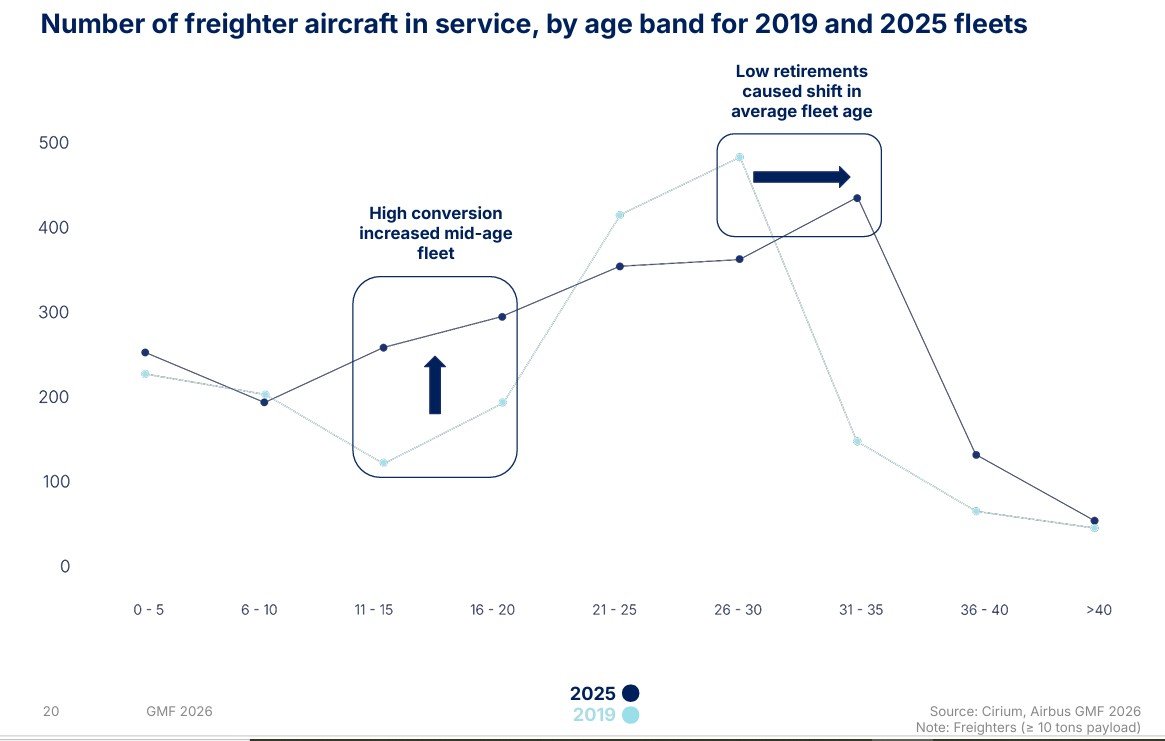
The worldwide freighter fleet has grown to more than 2,350 aircraft currently in service. Much of this expansion followed the air cargo boom during the Covid-era economic disruption, when airlines accelerated passenger-to-freighter conversions and postponed aircraft retirements to take advantage of favourable market conditions.
That period left the industry with a larger but older fleet. Airbus estimates that approximately two-thirds of today’s freighters will need to be replaced over the next 20 years.
Francois Cabaret, Airbus’ head of market forecasts, explained during a virtual media briefing that the average age of cargo aircraft is considerably higher than it was five or ten years ago. He said cargo operators would progressively retire their oldest aircraft and replace them with either newly manufactured freighters or converted passenger jets as suitable capacity becomes available.
Aircraft retirements increased to approximately 75 in 2025, according to aviation data provider Cirium.
Replacement demand is particularly significant in the 80-tonne payload category. Cabaret indicated that operators are likely to favour newly built aircraft in this segment because widebody passenger aircraft often accumulate substantial operating hours over their lifetimes, making conversion less attractive in certain cases. New-generation freighters can also offer improved range and payload performance.
Airbus and Boeing compete for the next generation of freighters
Airbus does not currently operate a conversion programme for large widebody aircraft and is instead positioning its A350F as a new-build solution for the long-haul cargo market. The freighter is derived from the manufacturer’s A350 passenger aircraft platform.
Boeing, meanwhile, faces competition from conversion specialists offering freighters based on the 777. Israel Aerospace Industries and US-based Mammoth Freighters have secured dozens of conversion orders as their first aircraft are delivered to customers.
Airbus does offer passenger-to-freighter conversion services for its medium-widebody A330-300 and the A321 standard airliner, allowing it to serve other segments of the cargo market.
Crawford Hamilton, Airbus’ head of freighter marketing, reiterated that the company expects to deliver the first A350F to a customer in late 2027, maintaining its previously announced schedule.
The aircraft completed its first initial test flight last month and is expected to undergo a further nine months of flight testing. European civil aviation authorities are then expected to certify the aircraft for commercial operations, subject to the successful completion of the programme.
Alongside flight testing, Airbus is conducting repeated loading and unloading exercises with different types of cargo-handling equipment. These activities are intended to help develop efficient operating procedures that airlines can adopt when the aircraft enters service.
Airbus has secured 115 A350F orders from 14 identified customers and one undisclosed customer. Boeing has received 81 orders for its next-generation 777-8 freighter.
With replacement requirements accounting for a substantial share of future demand, and new trade routes and technology-related shipments continuing to reshape the market, Airbus expects the global freighter fleet to expand steadily through 2045. The scale of that expansion will depend on the evolution of international trade, airlines’ fleet renewal decisions and manufacturers’ ability to deliver new-generation cargo aircraft.