Air Nov 6, 2026
Air cargo demand rises 6% in October, but hopes of a stronger peak season fade
Global air freight volumes continued their year-on-year growth for the seventh consecutive month, while spot rates climbed 29% compared with October 2025. However, limited capacity expansion, declining e-commerce shipments between Asia and Europe and the gradual return of ocean services to the Red Sea are raising questions about the market's growth prospects.
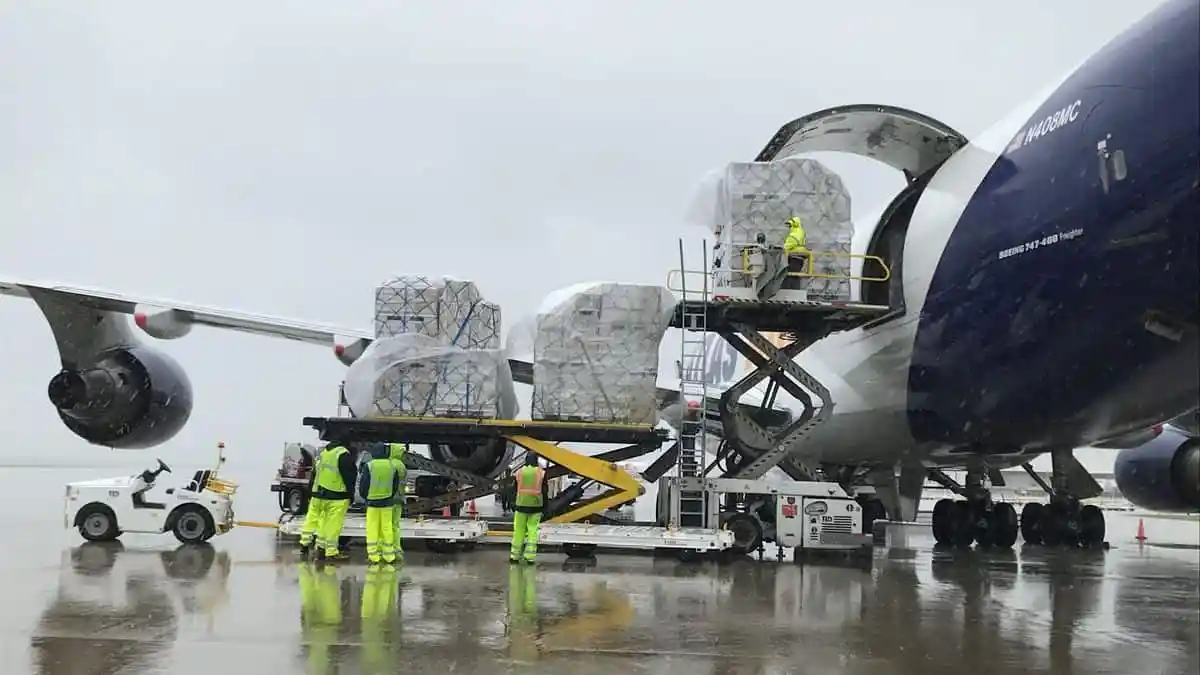
Global air freight demand maintains its upward momentum
Global air cargo demand continued to expand in October, recording a 6% year-on-year increase, according to the latest market analysis published by Xeneta. This marks the seventh consecutive month of annual growth since volumes declined by 3% in March, following the escalation of the Middle East conflict and the resulting closure of Gulf airspace.
Despite this sustained performance, the market is showing few signs of an additional surge ahead of the end-of-year peak season. Neither a sharp deterioration in capacity availability nor a significant acceleration in freight rates has emerged to suggest that a late-season volume peak is approaching.
Niall van de Wouw, Chief Airfreight Officer at Xeneta, noted that demand continues to progress steadily, without displaying the characteristics of an exceptionally strong peak season.
"The market is continuing its steady pace of growth, as we’ve been reporting since March. It’s strong, but it’s not a ‘peak’ season, and time is quickly running out for volumes to shift higher. I am already seeing Christmas trees and listening to Mariah Carey and Wham! as I travel through airport terminals," he said.
The latest figures therefore point to a market that remains active but is gradually running out of time to register a more substantial seasonal acceleration.
Air cargo spot rates climb 29% year on year
Pricing developments confirm the continued strength of the air freight market. In October, global spot rates for shipments booked up to one month in advance averaged USD 3.11 per kg, representing a 29% increase compared with the same month last year.
The annual rate increase has widened for two consecutive months, following a period of moderation between June and August. On a monthly basis, spot rates advanced by 4% as the market entered the fourth quarter.
Capacity availability remains a decisive factor behind these developments. After increasing by 2% in September, global air cargo capacity recorded no year-on-year growth in October.
With shipment volumes continuing to exceed the expansion of available capacity, Xeneta's dynamic load factor increased by two percentage points year on year, reaching 63%.
This indicator measures capacity utilisation by taking into account the volume and weight of cargo transported in relation to the available capacity.
Transatlantic and transpacific routes record further rate increases
October brought higher spot rates across all 10 major international trade corridors monitored in Xeneta's monthly analysis.
The most significant monthly increase occurred on the westbound transatlantic route, where rates from Europe to North America rose by 10%, reaching USD 2.31 per kg.
The adjustment coincided with airlines moving to their winter operating schedules. The resulting reduction in available capacity is already influencing the prices carriers are quoting to freight forwarders in recent tender processes.
Across the Pacific, demand linked to artificial intelligence-related shipments continues to provide support to the market.
According to Rotate, chargeable cargo weight transported from Asia-Pacific to North America was approximately 15% higher year on year in October. Freighter capacity on the same corridor followed a broadly comparable growth trajectory.
Spot rates from Southeast Asia to North America increased by 3% month on month, reaching USD 6.34 per kg. The Northeast Asia–North America corridor also recorded an increase of 4%, taking rates to USD 6.21 per kg.
Return routes from North America to Europe also strengthened, although at a more moderate pace. Backhaul spot rates across the monitored corridors rose between 1% and 3%, with the North America–Europe route increasing by 3% to USD 1.15 per kg.
Asia–Europe air freight faces mounting demand uncertainties
Although air freight rates continued to rise between Asia and Europe in October, the outlook for this market is becoming less certain.
Spot rates from Northeast Asia to Europe increased by 4% month on month to USD 4.97 per kg. Meanwhile, shipments originating in Southeast Asia recorded a 3% increase, bringing rates to USD 4.35 per kg.
However, several structural developments could limit further growth, particularly the continued decline in e-commerce shipments and changes in the regulatory environment governing low-value imports into the European Union.
E-commerce traffic has been an important source of demand for freighter capacity between Asia and Europe in recent years. That contribution is now weakening.
Analysis conducted by Xeneta and Trade and Transport Group, based on China Customs data, shows that China's low-value and e-commerce exports to the EU declined by 61% year on year in the third quarter.
The downturn followed the introduction of the EU's €3 customs duty per item on 1 July. By comparison, China's overall exports to Europe recorded a smaller decline of 29%, partly because shipments to Russia more than tripled.
Further pressure is expected from the additional €2 handling fee per item introduced by the EU from 1 November. Nevertheless, Xeneta anticipates that its impact will remain relatively limited, given that e-commerce volumes have already fallen by more than half.
Capacity developments are adding another layer of uncertainty. Direct freighter capacity between Asia and Europe declined again in October, following the earlier loss of capacity on routes operating through the Middle East.
This has helped support pricing. China–Europe spot rates were 6% higher year on year in October, compared with a much stronger 38% increase on the China–North America corridor.
Europe is also benefiting less from the artificial intelligence-related cargo flows currently supporting transpacific demand.
According to the World Trade Organisation (WTO), Europe accounts for approximately one-tenth of trade in AI-related goods, despite representing more than one-third of global merchandise trade.
Red Sea recovery could divert freight volumes to ocean freight
Another key factor shaping the outlook for air cargo is the gradual resumption of container shipping through the Red Sea and Suez Canal.
Container shipping capacity scheduled to cross the Red Sea was around 50% of its pre-crisis level in October, according to ocean freight data from Xeneta.
More than half of Asia-Europe shipping capacity now passes through the Suez Canal in at least one direction, with some one-third of services running the route both ways.
This slow return could result in undoing some of the shift to air cargo that took place during the disruption to maritime supply chains.
Xeneta’s analysis of Eurostat data shows the correlation between schedule reliability of ocean freight and the proportion of air cargo in Asia-Europe trade.
Air freight accounted for 1.1% of EU import tonnage from Asia in 2023. This figure increased to 1.7% in 2024, a year when the Red Sea crisis led to a major impact on maritime operations with schedule reliability on Far East to Northern Europe routes declining from 28% to 9.3%.
Ocean’s reliability improved to 20% by 2025 and air freight’s share fell to 1.2%.
But in the first eight months of 2026, it crawled back up to 1.3%. This came after the closure of the Strait of Hormuz in February, which led to carriers delaying their planned return to the Suez Canal.
The latest Eurostat figures only cover the period up to August, and therefore do not yet reflect the impact of the more recent autumn resumption of Red Sea services.
Additionally, maritime schedule reliability between the Far East and Northern Europe was weak in October, at around 10%.
“Xeneta expects to see some shipments that switched to air freight mainly for reliability rather than speed gradually return to ocean transport as shipping schedules improve sustainably,”
This transition is expected to most likely begin in the second quarter of 2027. Meanwhile, air freight is likely to keep much of the cargo it picked up during the shipping disruption.
The company plans to provide further details on these developments in its 2027 Air Freight Outlook, which is expected to be published in the coming weeks.
Air freight rates could fall in 2027, but uncertainty persists
Outside of the current peak season, Xeneta’s base forecast shows a general downward trend for airfreight rates in 2027.
The fourth quarter is typically a tough time for long-term contract talks with many shippers inclined to delay negotiations during the busiest months of the year.
Consequently, several companies are already working on new tender processes, with the prospect of signing agreements in the first or second quarter of 2027.
That said, it is hard to reach mutually agreeable terms in today’s market environment.
“Freight forwarders really struggle to provide 12-month contracts due to the uncertainty around capacity and geopolitical developments, which makes it hard to offer competitive long-term pricing,” explained van de Wouw.
He said that the rate increases of the past two years were less the result of exceptionally strong demand, but more the result of limitations on available capacity.
Thus, a better balance between supply and demand, which could come about through an improvement in the situation in the Middle East, would exert downward pressure on freight rates.
That said, the market is still susceptible to surprises that can swiftly alter the outlook.
“Forwarders can always offer shippers deals for 12 months, but in the current market conditions they would have to include so much uncertainty that the price becomes uncompetitive. Over the last couple of years, it’s not been the demand that’s driven the rates up, it’s been the capacity available. If the situation in the Middle East improves, demand and supply will rebalance and rates will be lower. But things will come about. We don't know what or where but this is the lesson the market has learned. We can no longer term these ‘Black Swan’ events as they are now occurring too often. That makes it difficult for everyone to negotiate contracts, said van de Wouw.
Therefore the challenge for air cargo stakeholders will be to prepare for a potentially softer pricing environment in 2027, but while retaining enough flexibility to respond to geopolitical disruptions, changing trade flows and fluctuations in available capacity.
The October numbers, in the final analysis, reflect a market that is still expanding, but one in which capacity constraints, regulatory changes and the slow recovery of sea transport will be ever more important in shaping the direction of global air freight rates.
END OF REPORT