

A move from New York to Singapore gave Xeneta analyst Deborah Ong a different perspective on liner shipping one that has proved particularly valuable as she speaks with shippers about their logistics strategies and budgets for 2027.
At a Singapore Freight Budget Roundtable, Ong found that soaring surcharges are leaving shippers facing substantial additional costs. Bunker adjustment factors (BAF) have more than doubled since the beginning of the Iran war, adding further pressure to already elevated freight rates.
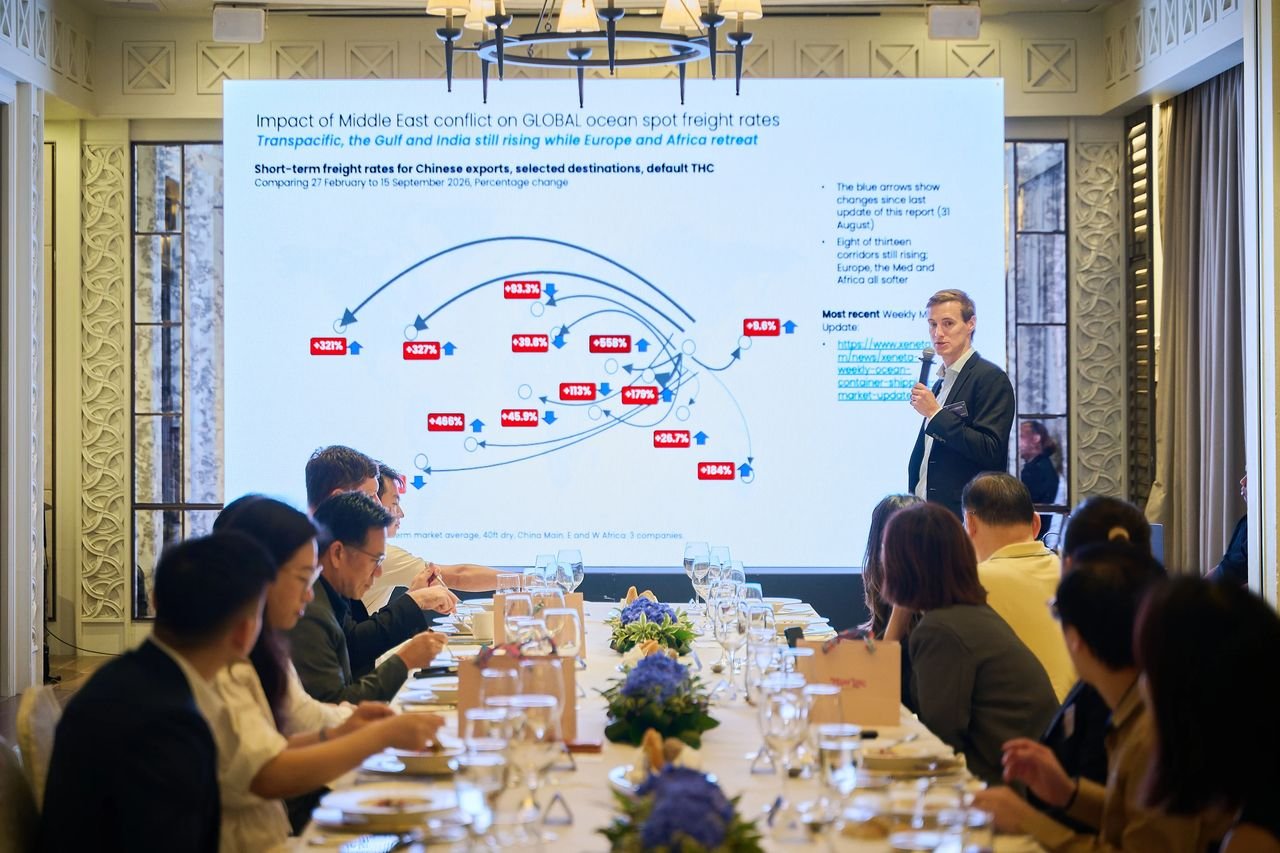
Spot rates have also risen sharply since the conflict began at the end of February. Rates to the Arabian Gulf have increased by 558%, while those to South America’s East Coast have climbed 466%. Rates to the US East Coast and West Coast have risen by 327% and 321%, respectively.
The dramatic changes in the spot market are also reshaping contract negotiations.
According to Ong, between 20% and 35% of shippers at the roundtable had chosen three-month rolling contracts, hoping that freight rates would eventually decline and allow them to secure longer-term agreements at lower costs.
Instead, that strategy has left some shippers exposed to the same elevated market conditions, without the negotiating leverage that a full tender process could have provided.
“Instead, they are now facing the same elevated market, without the leverage that a full tender process would have given them,” Ong explained.
Some carriers are also considering index-linked rates. However, shippers still have concerns over whether the available indexes are reliable enough and whether minimum quantities would be adequately protected under such arrangements.
The most intense discussion at the roundtable, however, focused on bunker fuel surcharges.
Although bunker prices have remained largely flat since late April, BAFs have continued to increase. On the Far East–Mediterranean trade, the BAF rose from $250 to $533 per FEU between February and the end of July. Over the same period, BAFs on the Far East–US West Coast route increased from $426 to $717 per FEU.
Ong said shippers increasingly feel that the contractual process has become difficult to predict, with surcharges being added after the base freight rate has already been agreed.
“Shippers described a market where the base rate is agreed and then surcharges arrive on top with little explanation,” she said.
“One attendee said it no longer feels like a contract, because every surcharge has to be negotiated as it appears.”
Shippers therefore want contracts to provide greater transparency around BAFs, with the base freight rate and surcharge clearly separated. However, such provisions would need to be established during the next tender process. Adjusting an existing contract in the middle of its term is widely regarded as impractical.
Additional pressure could also emerge on the Asia–US East Coast trade as peak El Niño conditions are expected between January and April. The weather phenomenon could restrict both the number of vessels able to transit the Panama Canal and the amount of cargo those vessels can carry.
At the same time, the US West Coast is already experiencing congestion, limiting its ability to absorb cargo that could otherwise be rerouted.
“The US West Coast is already congested and cannot absorb rerouted cargo,” Ong said.
Despite this risk, only a small number of shippers are currently developing contingency plans to move additional volumes to the West Coast.
The roundtable also highlighted that shippers are not necessarily measuring their logistics budgets against the same objective. Some are seeking the right balance between cost and reliability, while others are primarily concerned with securing vessel space or ensuring that deliveries arrive as promised.
But there was one notable point of agreement: the lowest possible freight rate was not the main objective.
“Not one of them [shippers] said the goal was the lowest rate,” Ong noted.
“The phrase that stuck with me was that budget is about assuring supply.”
Looking ahead to the approaching European contract season, Ong believes discussions around freight budgets can be structured around a more practical framework.
Shippers should first establish their baseline costs while taking into account the impact of volumes, changes in trade mix, network adjustments and broader macroeconomic price effects. BAFs should then be treated separately, with their future development dependent in part on whether a ceasefire is reached.
The message emerging from the discussions is increasingly clear: for shippers planning the year ahead, the value of a contract is no longer determined solely by its headline freight rate. Predictability, transparency and the ability to secure supply are becoming just as important as cost.