Business Nov 12, 2026
Fitch upgrades XPO to investment-grade status as debt reduction strengthens its financial position
The rating agency raises XPO to BBB-, placing the LTL carrier above the investment-grade threshold for the first time among the three major agencies. Moody’s and S&P Global remain one notch below that level, despite their recent upgrades.
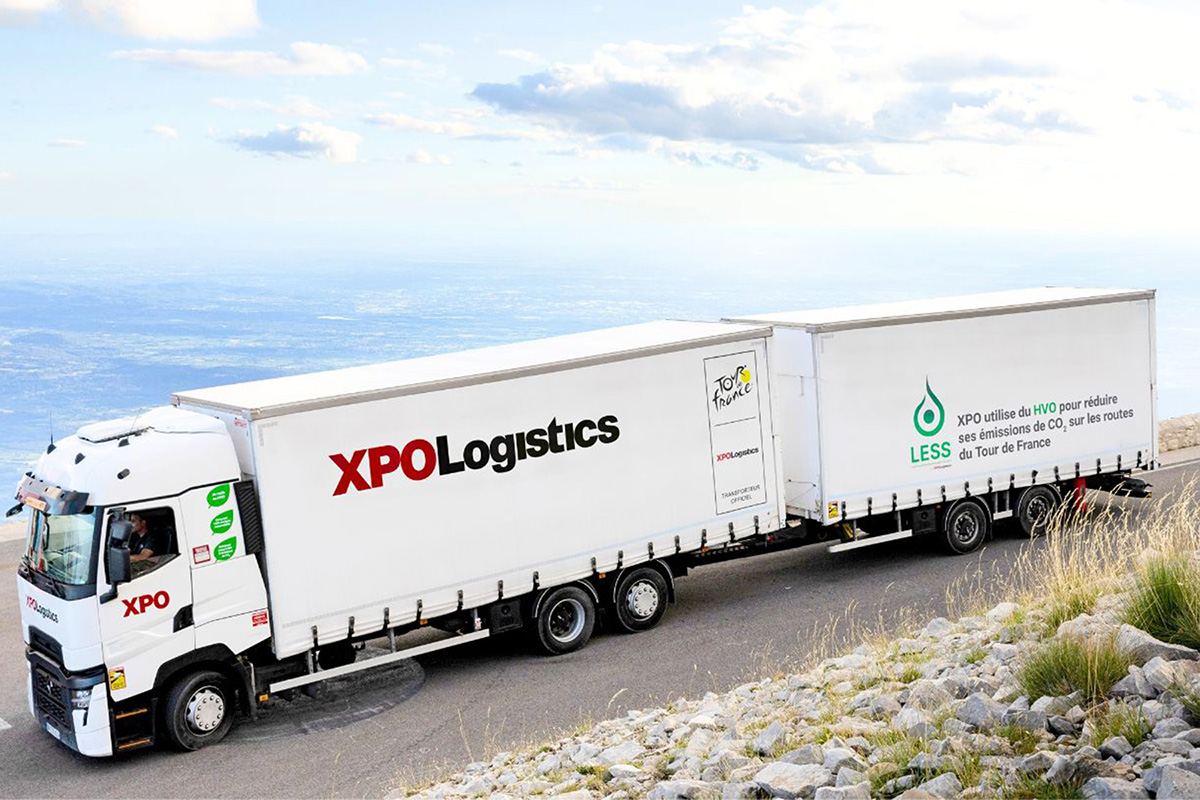
Fitch Ratings upgraded the American less-than-truckload (LTL) carrier XPO, making a big step forward in its credit standing to BBB-. The move pushes the company into investment-grade territory at Fitch, crossing the line between investment-grade debt and speculative-grade obligations.
The upgrade means XPO is now rated as an investment-grade borrower by one of the three major credit rating agencies. But Moody’s and S&P Global Ratings have not come to the same conclusion yet. XPO was raised by one notch by both agencies – to Ba1 and BB+ respectively, just a few months ago. These are considered equivalent ratings, but still just below investment grade.
Fitch had previously rated XPO BB+ in March 2023 and its ratings have been unchanged since then.
The agency cited stronger operational and commercial execution and structural improvements in the company’s business performance and cash generation in a report released late last week. Fitch says the pace of such improvements is outpacing the wider industry.
The agency also pointed out the significant repayments of gross debt by XPO as an indication of a quick and material commitment to the leverage targets publicly communicated for 2026.
Debt repayment is driven a lot by upgrade
XPO, being a public company, provides a wealth of visibility into its financial performance as opposed to privately held businesses which may only offer information concerning publicly issued debt.
The latest financial indicators are showing a significant improvement. Revenue increased 12.4% year-over-year to $2.37 billion between the third quarters of 2025 and 2026. Net income also leaped from $82 million to $181 million, while the adjusted operating ratio improved from 82.7% to 80.1%.
However, the magnitude of debt reduction appears to be particularly important in Fitch’s view. XPO reduced debt by more than $1 billion in the nine months ended September 30, compared with $50 million in the comparable period in 2025.
Cash-generation capacity is another important financial strength measure for the rating agencies. Fitch expects XPO’s free cash flow (FCF) to be about $500 million in 2026 and 2027, based on its own calculations. That would be a big jump from about $270 million in 2025.
Fitch also said it uses a proprietary methodology to calculate cash flow, and its figures may differ from the company’s reported measures.
Leverage indicators suggest further improvement
XPO’s debt ratios are another sign of the company’s changing financial position.
Fitch expects the carrier’s EBITDA-to-debt and EBITDAR-to-debt ratios to be in the low 2.0x range this year. EBITDAR includes rental costs not included in EBITDA. This compares with respective 2025 ratios of 2.8x and 2.7x.
The agency also pointed to XPO’s focus on internal initiatives instead of large-scale external growth. The company’s plan to balance debt repayments and share buybacks in 2026 is considered to be in line with controlling financial leverage.
The strategy is an important element of Fitch's assessment as it signals that XPO intends to consolidate its financial position rather than pursue accelerated expansion through major acquisitions.
XPO's position compared with other transport companies
Fitch also examined XPO's credit position against three other companies: Brink's, TFI International and Forward Air.
The comparison with Brink's is largely limited to the fact that both businesses operate in transportation. Their activities, however, are considerably different, with Brink's specializing in the secure transportation of cash and valuables rather than the freight typically handled by an LTL carrier.
TFI International, listed on the NYSE under the symbol TFII, does not currently have a credit rating from Fitch. Nevertheless, the agency indicated that the company's historical average debt load has generally ranged from the mid-1.0x level to the low-2.0x range.
Forward Air presents a different financial picture. Fitch forecasts that its debt load will exceed 6.0x in 2026 before improving to the mid-5.0x range by 2028.
The agency currently assigns Forward Air (NASDAQ: FWRD) a B rating with a negative outlook. This places the company five notches below XPO's newly upgraded BBB- rating.
Despite the improvement in XPO's credit profile, Fitch has maintained a stable outlook. This indicates that the agency does not anticipate an upgrade or downgrade in the foreseeable future.
Fitch is more bullish on the LTL industry.
The upgrade also comes amid generally cautious assessments of the trucking industry by credit rating agencies in recent years. The overall outlook has been subdued, but the less-than-truckload operators have been viewed somewhat more favorably than the broader industry.
Fitch’s latest report is more optimistic about long-term profitability of LTL carriers.
“Given the high barriers to entry from established asset-based networks, the agency expects the sector to be resilient over economic cycles,” it said.
It also believes XPO and other large LTL players have shown more pricing discipline throughout freight cycles than companies in the truckload market.
Contractual relationships are another source of stability. Spot truckload rates can be more volatile in relation to the market, but LTL carriers have more visibility thanks to agreements with customers. However, Fitch points out that such contracts tend to be for a period of around one year.
Stock performance, financial discipline under consideration
The stock has done well so the financial position of XPO has improved as well. The stock is up about 36.7% from the beginning of the year. They are up about 3% over the last month, but down approximately 7% over the last three months.
The company does not currently pay dividends to shareholders. Fitch has specifically cited a possible change in XPO’s capital allocation strategy as one of the developments that could influence its credit assessment.
Among the risks cited are the introduction of a large dividend, or a more aggressive M&A strategy that could limit the company's financial flexibility.
XPO’s last major acquisition came in 2024, when it acquired real estate assets being spun off from the bankruptcy of Yellow Corp. The transaction included properties to facilitate the expansion of XPO’s service center network.
XPO is crossing an important credit threshold with Fitch with its new BBB- rating. Maintaining that status will depend on the company's ability to keep generating cash, to keep reducing debt and to maintain the financial discipline that has underpinned the latest upgrade.
END OF REPORT