

The global container shipping orderbook has hit a new high after substantial newbuilding commitments by MSC and South Korean carrier HMM. The latest contracts include 28 container ships of more than 13,000 TEU to the pipeline, taking the post-2009 orderbook to 16.2m TEU, equivalent to 46.5% of the existing fleet.
MSC forms the bulk of the latest expansion. The Swiss-based shipping group has placed an order for 20 vessels of 24,000 TEU capacity with Hengli Heavy Industries in Dalian, China. MSC’s orderbook for ships over 20,000 TEU has now grown to 62 vessels following the deal.
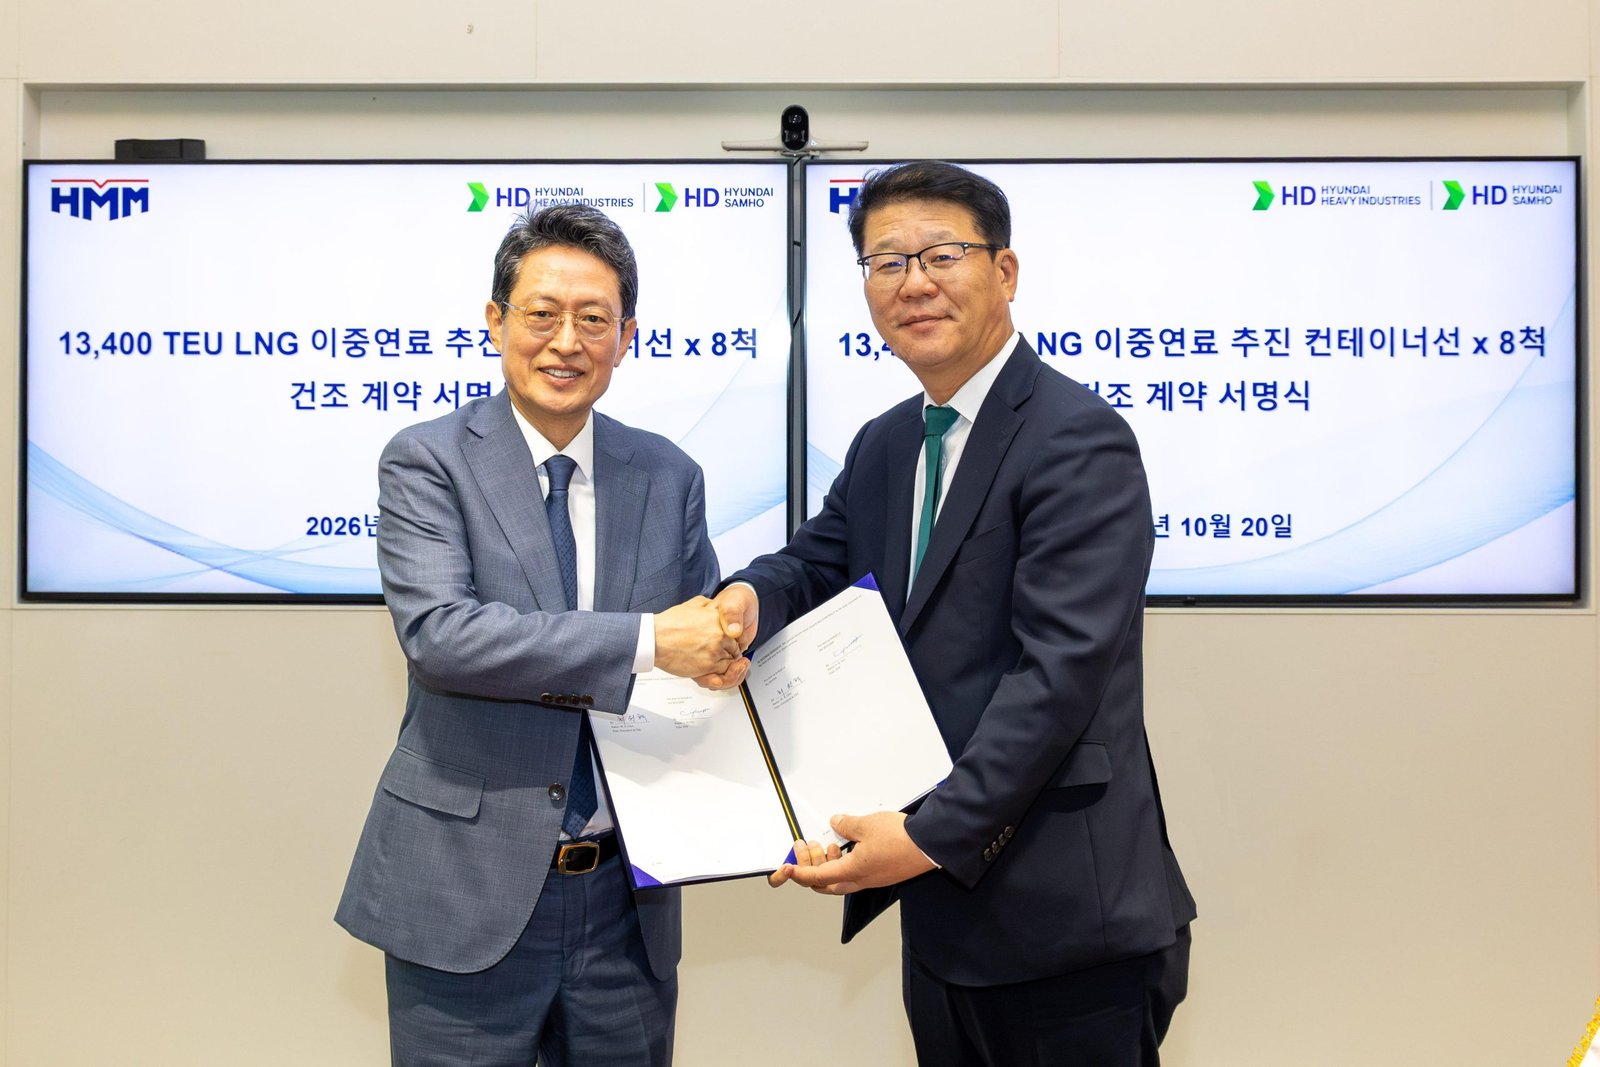
HMM has furthered its fleet renewal and expansion program with a contract for eight LNG dual-fuel container ships with a capacity of 13,000 TEU. The order, valued at around $1.5 billion, was awarded to Hyundai Heavy Industries and HD Hyundai Samho.
The new vessels will be deployed on HMM’s Far East-India-Mediterranean service to support its capacity and operational requirements on those trade lanes, the company said.
HMM expands its fleet with further acquisitions
Besides its newbuilding orders, HMM has inked a resale contract for four more ships, which consist of three 2,900 TEU vessels and one 1,700 TEU unit. These vessels are designed for regional feeder service, extending the carrier’s reach on shorter-haul shipping networks.
The acquisitions are part of a wider investment strategy including fleet expansion, logistics infrastructure and future technologies. HMM said in a company statement its total investments in these areas this year reached roughly KRW 6 trillion, or more than $4.5 billion.
Deliveries continue to exceed scrapping
The latest ordering activity comes as the global container fleet continues to grow with demolition remaining very limited. According to Linerlytica data, 20 container ships with a total capacity of 162,206 TEU were delivered in the last 30 days. During the period, only one vessel was removed from the fleet, the 2,800-TEU GFS Pride, which sank in the Arabian Gulf after an attack.
Since demolition volumes peaked at around 100,000 TEU in 2017, ship recycling has been subdued. The downturn became especially pronounced after the Covid-19 pandemic, when strong demand and a buoyant container shipping market encouraged operators to keep vessels rather than send them for demolition.
The massive scale of the resulting capacity growth is highlighted by the figures from shipbroker Braemar. Some 1.12 million TEU of new capacity has joined the global fleet since the start of the year, against just 40,000 TEU scrapped. Fleet capacity has grown by more than one million TEU.
For the period until 1 October, newbuilding orders placed since January had reached 4.1 million TEU excluding the latest contracts announced by MSC and HMM. The new orders will increase the pipeline of vessels entering service in the next few years.
Changes to the Red Sea route could free up more capacity
The outlook for global container shipping capacity is also being shaped by the expected return of carriers to their traditional routes through the Suez Canal. Shipping companies are expected to be back to full capacity on the Cape of Good Hope routing by the end of the first quarter of 2027.
If the shorter route were to be reintroduced, a further 1 million TEU of effective capacity would be released to the global market. Current vessels spending additional time sailing around southern Africa could complete voyages more quickly, increasing the amount of capacity available for deployment across international services.
This adjustment is coming with continued growth in container volumes. Container Trades Statistics reported an increase in volumes of 17.5% in August and the cumulative growth for the year to date reached 4.8%.
Fleet growth slowed in 2026 but the combination of a rapidly expanding orderbook, continued vessel deliveries and very low demolition levels should lead to accelerating capacity growth over the next three years.
The latest MSC and HMM contracts therefore confirm a trend already underway in the container shipping industry, where new vessel supply is growing at the same time carriers are also preparing for a possible release of more effective capacity through shorter trading routes. Market conditions for the years ahead will still be heavily influenced by the size of the orderbook and the pace of fleet growth.