Business Nov 18, 2026
Oil market slump drags US benchmark diesel prices below $6 a gallon
U.S. diesel costs are falling sharply as crude prices drop, with some respite seen from expectations of higher global oil supply in 2027. But the persistent uncertainty over shipments through the Strait of Hormuz is a significant factor in market volatility.
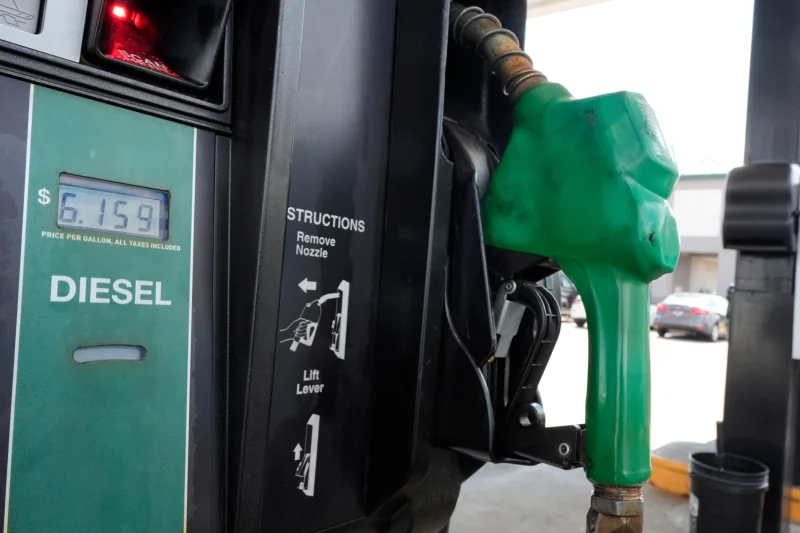
With lower oil prices, retail fuel prices are following suit and the US diesel market is beginning to ease. The most recent figures from the Department of Energy and the Energy Information Administration (DOE/EIA) indicate the national average retail diesel price fell 19 cents per gallon, effective Monday and released Tuesday, to $5.937 per gallon.
That’s the steepest weekly decline since June 22, when prices dropped by 22.7 cents a gallon. It is also the third largest weekly fall registered amid the highly volatile movements that have marked the diesel market since the start of military operations by the United States and Israel in early March.
The latest slide takes the benchmark below the $6-a-gallon mark for the first time since Sept. 8. That’s 59.2 cents cheaper than the all-time high of $6.529 a gallon reached Sept. 22.
The American Automobile Association’s (AAA) national daily average has slipped beneath the DOE/EIA benchmark as well. The AAA figure was $5.9848 Tuesday after falling below $6 a gallon Monday.
Wholesale markets retreat, more cuts possible
The latest fall is a reflection of a wider sell-off across petroleum markets in recent trading sessions on the CME commodity exchange. Since retail fuel prices usually follow changes in wholesale markets with some lag, further reductions at the pump could occur if the downward trend continues.
Ultra low sulphur diesel (ULSD) futures ended at $4.4216 a gallon on Nov. 2, the first trading day of the month. But prices took a particularly steep dive Monday, dropping 20.47 cents to close at $4.0818 per gallon. That leaves ULSD down about 34 cents in the first half of November.
Diesel futures have generally followed the downward trend in crude oil prices. But the big spread between diesel and crude, still unusually wide by historical standards, has for the most part held. That gap still exists when you compare Brent crude to first-month and second-month ULSD contracts.
Brent crude settled at $104.77 a barrel on the first trading day of November. It had dropped to $92.44 a barrel by Monday, close to its October 10 settlement low of $91.49.
Oil prices pressured by IEA supply outlook
The recent market correction leaves many asking what is driving prices down, particularly after some analysts had predicted a prolonged period of high oil prices.
Much of the changing picture of the market is based on the International Energy Agency’s (IEA) November oil supply and demand report. The agency’s latest assessment has confirmed expectations of ample crude availability, in line with projections the agency had made a year ago.
The prospect of a large oversupply was already included in the 2026 outlook. But the Middle East conflict disrupted those expectations and altered the pattern of world oil flows significantly.
The IEA has revised its view on the supply recovery in 2027 to be better. Global oil production is projected to rebound by 6.6 million barrels per day (b/d) after a decline of 4.8 million b/d in 2026, the agency said. That would put average supply at 108.1 million barrels a day next year.
The signs of recovery are already there. The IEA estimated that global oil supply rose by 3 million b/d in September and by another 2.3 million b/d in October to 105.4 million b/d.
Conversely, world oil demand is expected to average around 104.3 million b/d this year, leaving a large gap between supply and consumption.
But the forecast surplus will also be used to refill depleted global inventories. Worldwide inventories of oil have fallen by about 460 million barrels since the war began, the IEA said.
The recent improvement in supply is mainly because of higher crude shipments passing through the Strait of Hormuz. But there are still more restrictions on refined petroleum products.
Strait of Hormuz remains a big source of uncertainty
"The crude flows are improving but the outlook is fragile, as the shipping conditions through the Strait of Hormuz are far from stable.
“Current oil flows from the Middle East through all available routes are estimated to be in the range of 16 million to 17 million barrels per day,” Amrita Sen, director of market intelligence at research firm Energy Aspects, told CNBC. Normal flows before the war were about 20 million barrels per day.
Sen also pointed to the fragility of these supplies, saying loadings had again started to fall over the past week.
One of the most vocal bulls in the market in recent months has been Jeffrey Currie, chief executive of Real Macro and a former head of commodities research at Goldman Sachs. "The situation in the Strait of Hormuz is one where market participants cannot know for sure whether passage is effectively open or closed," he said in comments to CNBC.
"Although more oil is now flowing to the world market, the additional supply is easing immediate supply pressures but not necessarily lowering the cost of future deliveries," Currie said.
He described the market as trapped in a limbo, with crude prices lingering at around $95 a barrel. “We are not in a position to see a big upward or downward movement in prices under current conditions,” he said.
The market has little visibility on how the disruption will ultimately be resolved without a lasting resolution to the situation surrounding the Strait of Hormuz, Currie also warned.
The recent fall in diesel prices has provided the global oil and transport industries with a little short-term relief. However, with the uncertainty of Middle Eastern supply routes, depleted inventories and the prospect of stronger production in 2027, the direction of energy prices remains closely tied to geopolitical developments.
END OF REPORT