

A hopeful sign for the less-than-truckload (LTL) sector is that Old Dominion Freight Line has notched the first year-over-year gain in freight tonnage in more than two years. But the carrier’s latest results also underscore the challenges facing the industry as companies continue to grapple with patchy demand for freight, high operating costs and uncertainty over the strength of any recovery.
During the third quarter earnings update Wednesday, Old Dominion’s management pointed to opportunities to gain market share, with customers seeking multi-year contracts and third-party logistics providers seeking long-term commitments to capacity. While these commercial developments are positive, executives highlighted that a more significant improvement in demand is needed to achieve the results that are typically associated with a freight upcycle. The resolution also pointed out an important factor, that is, record-high energy prices.
Old Dominion (NASDAQ: ODFL) reported earnings per share of $1.65 Wednesday before the market opened. The figure was $0.04 above the consensus estimate from analysts and $0.37 higher than the same period last year.
Revenue for the quarter was $1.59 billion, up 13 percent year-over-year. Excluding fuel surcharges revenue growth was 5%. The bottom line was also $20 million better than analysts’ expectations, despite a 48% year-over-year increase in diesel fuel prices during the quarter.
Pricing power more than offsets weaker shipment volumes
The carrier’s daily tonnage was unchanged compared with a year earlier, but a 13% increase in yield, measured in revenue per hundredweight, helped lift revenue overall. Yield excluding fuel surcharges was up 5%, slightly better than the guidance earlier provided by management of 4% to 4.5%.
Shipment activity was mixed below the surface. Year-over-year shipments were down 2%, but a 2% increase in average weight per shipment countered that decline and contributed to stabilizing overall tonnage.
The quarterly performance also showed improving monthly trends. Tonnage was down about 1% year over year in both July and August before rising 1.6% in September. The good news kept on coming in October.
Comparisons to last year are still relatively favorable for carriers. Old Dominion’s tonnage dropped 10.7% year over year in the fourth quarter of 2025, making today’s performance a lower comparison to measure against.
The overall LTL market has been showing signs of improvement, too. After the sector returned to positive territory for the first time in March, cumulative year-over-year tonnage growth for publicly traded carriers accelerated in August. Meanwhile, manufacturing expanded for a ninth straight month in September, although inflation concerns still hung over the outlook.
The freight that had been moving away from the LTL sector is also starting to come back as the depressed truckload market changes the competitive landscape.
Capacity constraints create opportunities to capture market share
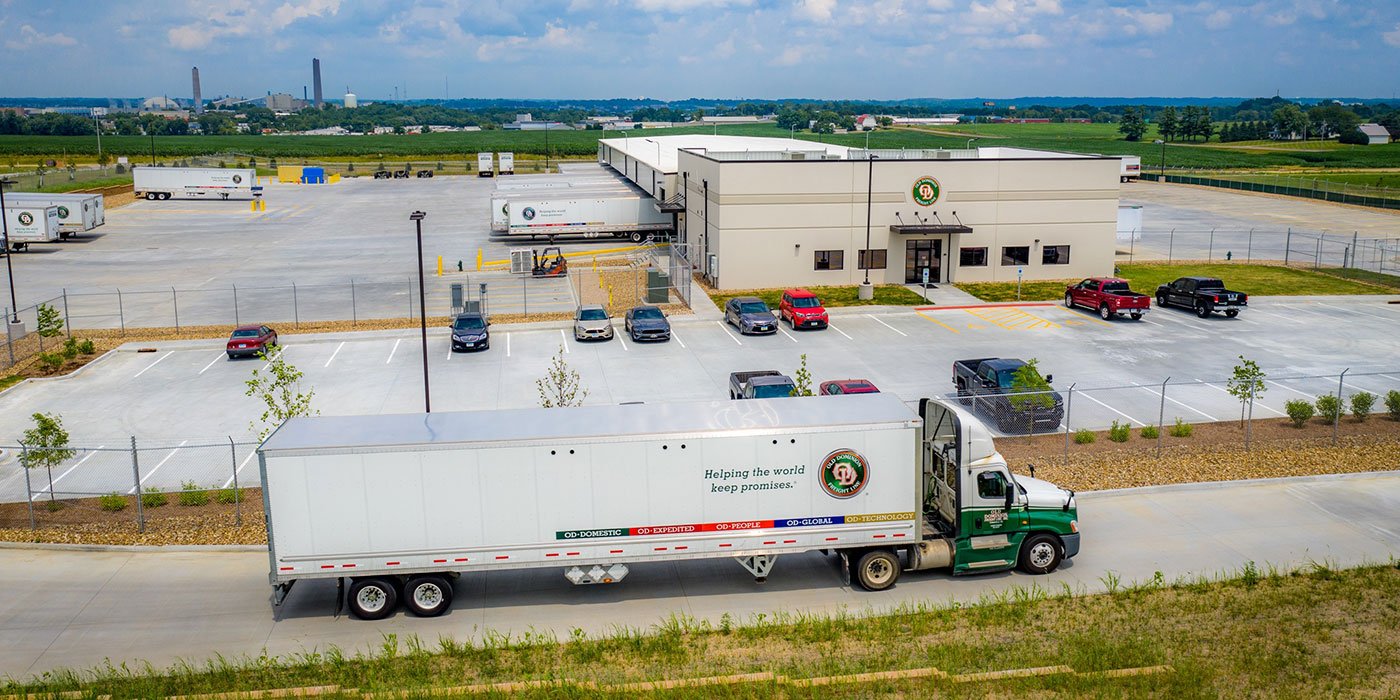
Old Dominion is still operating with over 35% excess door capacity which leaves it with plenty of room to take on more freight without the need for immediate major infrastructure expansion.
The company believes the available capacity will enable it to take business from competitors with tighter operating constraints and service failures. Customers needing reliable transportation capacity may increasingly prefer carriers able to maintain service quality while offering longer-term commitments.
During periods of stronger demand for freight, Old Dominion usually outpaces the overall market by 9 to 10 percentage points. The question is whether that historic edge will translate into a sustained recovery, and that will depend on whether the current uptick in tonnage becomes a broader, longer-term trend.
Pricing performance is another key part of the company’s strategy.
Higher shipment weights put pressure on yields lower, but this was partially offset by a slight increase in average haul distance. Revenue per shipment, excluding fuel surcharges, increased 7% year-over-year.
Old Dominion also announced a 4.9% general rate increase effective October 5, further emphasizing its commitment to pricing discipline as carriers adjust to changing market conditions.
Third Quarter Earnings Beat Expectations
The company operated at a ratio of 71.5% during the quarter. This metric, which measures operating expenses as a percentage of revenue, improved 280 basis points versus last year and was 40 basis points better than the midpoint of management’s guidance.
The prior outlook had expected a sequential deterioration of 150 to 200 basis points from the second quarter’s unadjusted operating ratio of 70.1%.
There were also improvements in operational productivity. Shipments per employee per day increased 2% year over year and revenue per shipment, net of fuel surcharges, increased 15.5%.
Costs rose more slowly than revenue per shipment. Cost per shipment was up 11% for a healthy 440-basis point spread between revenue and cost growth.
These numbers show how pricing power and operating efficiency have kept Old Dominion profitable even with relatively modest freight volume growth.
October revenue rises as yields continue to climb
Preliminary October operating trends reflect continued revenue growth. Revenue per day rose 22% year over year, helped by a modest rise in tonnage and a roughly 20% rise in yield.
Yield growth, excluding fuel surcharges, rose to between 5.5% and 6%. That was even as heavier shipments added further pressure, with average shipment weight up 3% year-on-year in October.
“Stronger pricing and firmer tonnage combine to suggest a better starting point for the fourth quarter.” The sustainability of these gains, however, will depend on demand conditions and the extent to which high fuel prices continue to be a drag on reported revenue.
The fourth quarter outlook is for better than usual seasonal performance.
Old Dominion projects fourth-quarter revenue of $1.54 billion to $1.58 billion. The forecast is above the market consensus estimate of $1.51 billion and calls for above-normal seasonal performance.
The company expects to post a better operating ratio than it normally sees in the last quarter of the year.
Historically Old Dominion’s operating ratio deteriorates 200 to 250 basis points in the third and fourth quarters. Management expects the company to be at the better end of that range this year, which would mean an operating ratio of 73.5% in the fourth quarter.
That would be a 320-basis-point improvement from the fourth quarter of 2025.
Nevertheless, there are still many uncertainties about costs. An annual insurance adjustment could move the operating ratio in either direction by about 20 basis points. Higher healthcare costs and operating supply costs related to fuel could also weigh on performance.
“Management noted that orders are holding up reasonably well, with third quarter shipment volumes and tonnage a little better than typical seasonal trends. Yields have also continued to beat to the upside.
The outlook for Old Dominion’s incremental operating margin is 43% in the fourth quarter vs. 50% in the third quarter. The company expects the improvement in profitability to continue, but the trade-off between incremental revenue and operating costs will be less favorable than in the previous quarter.
Key performance indicators show the company’s operating trends
The company’s latest numbers show the different forces behind its performance. Better pricing and improving tonnage are supporting revenue, while shipment volumes and operating costs remain key variables for the coming quarters.
| Old Dominion Freight Line | Q3/26 | Q3/25 | Y/Y Gross Change | Y/Y % Change |
|---|---|---|---|---|
| LTL: | ||||
| Tonnage/Day | 32,194 | 32,231 | -37 | -0.1% |
| Shipments/Day | 43,332 | 44,201 | -869 | -2.0% |
| Pounds/Shipment | 1,486 | 1,458 | 28 | 1.9% |
| Revenue/Hundredweight (cwt) | $38.40 | $33.88 | $4.52 | 13.3% |
| Revenue/Hundredweight (ex-fuel) | $30.25 | $28.78 | $1.47 | 5.1% |
| Revenue/Shipment (ex-fuel) | $449.47 | $419.67 | $29.80 | 7.1% |
| Length of Haul (miles) | 912 | 909 | 3 | 0.3% |
| Average Headcount | 20,202 | 21,073 | -871 | -4.1% |
| Shipments/Employee (per day) | 2.14 | 2.10 | 0.05 | 2.3% |
| Consolidated: | ||||
| Revenue | $1,590.7 | $1,406.5 | $184.2 | 13.1% |
| Operating Ratio | 71.5% | 74.3% | -280 bps | -3.8% |
| EPS | $1.65 | $1.28 | $0.37 | 28.9% |
Revenue in millions.
Data source: Old Dominion’s key performance indicators.
Investors are still worried about sustainability of earnings
Old Dominion shares were down 5.5% by midday Wednesday, as the S&P 500 rose 0.2%.
Part of the concern among investors is how high diesel prices will impact the financial performance of transportation companies. Higher fuel prices can increase fuel surcharge revenue, which can enable LTL carriers to turn a profit that may not be sustainable when fuel prices drop.
Markets are questioning the industry’s longer-term growth prospects, even with the recent return to expansion in the manufacturing sector.
The key question for investors is whether Old Dominion’s pricing power, improved tonnage and available capacity can translate into continued growth once the revenue effects from fuel normalize and underlying freight demand becomes the primary driver of results.
Why it matters to the logistics industry
Old Dominion’s third quarter results are a key indicator of conditions across the LTL market. The company’s return to positive tonnage growth bodes well for the stabilization of freight activity and its revenue and profitability figures demonstrate the value of pricing discipline in a tough operating environment.
The results however are not yet indicative of a broad based recovery. The carrier remains very reliant on yield improvements, and management has said that it needs more of a demand increase to get the stronger results that are usually seen in an industry upcycle.
The coming quarters will therefore be key to see if recent gains are the start of a sustained freight recovery or more a function of pricing power, favorable comps with the prior year and the effects of higher fuel costs.