

Global airfreight demand continued to expand in September, but the combination of tighter capacity, higher utilisation and elevated operating costs is changing the way shippers secure freight capacity.
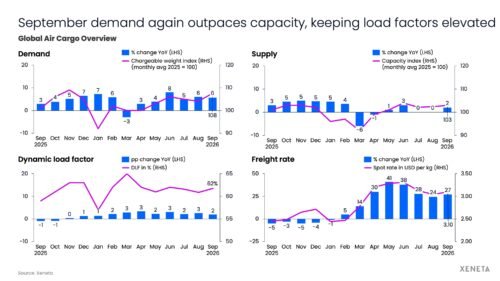
According to the latest data from Xeneta, global air cargo volumes increased 6 percent year-on-year in September, following growth of 6 percent in August and 5 percent in July. The figures confirm that demand remained resilient throughout the third quarter, even as market conditions became increasingly difficult to predict.
Capacity, however, failed to keep pace. Available capacity increased by only 2 percent year-on-year in September, lifting Xeneta’s dynamic load factor, its measure of capacity utilisation, by two percentage points to 62 percent.
The tighter balance between demand and supply continued to feed into pricing. Global airfreight spot rates averaged US$3.10 per kg during September, an increase of 27 percent year-on-year and 2 percent compared with August.
The upward movement coincided with the traditional seasonal upswing at the end of the third quarter. Higher jet fuel costs added another layer of pressure, with Brent crude briefly climbing above US$100 a barrel in early September amid continuing tensions in the Middle East.
Shorter contracts gain ground as shippers seek flexibility
One of the clearest signs of changing market behaviour is emerging in the way shippers are purchasing airfreight capacity.
Xeneta’s analysis of new contracts beginning in Q3 2026 found that 60 percent were agreed for three months or less. A year earlier, that share stood at 25 percent, while the figure was 47 percent in Q2.
Three-month agreements represented 42 percent of new contracts, compared with 16 percent in Q3 2025. At the other end of the spectrum, the share of 12-month contracts fell from 40 percent to 25 percent. Agreements lasting more than one year represented just 3 percent of newly contracted business.
For shippers, the shift reflects growing caution around fixed annual pricing at a time when market conditions can change rapidly.
Niall van de Wouw, Xeneta’s chief airfreight officer, said companies were increasingly looking for pricing structures capable of adjusting to market movements rather than locking them into fixed annual rates.
“A one-year fixed rate deal doesn’t fit the current conditions.”
Xeneta describes the emerging approach as “floating mechanisms”, under which a base rate is adjusted in line with movements in the wider market.
“There is a high degree of realism in the way shippers are approaching the market,” van de Wouw said. “There remains a lot of instability and that’s making it almost impossible for shippers to make long-term capacity deals without having T&Cs in place to deal with these volatile conditions.”
China-Europe e-commerce flows come under pressure
Changes in e-commerce traffic are also reshaping the global airfreight market, particularly across the major China-Europe and China-US corridors.
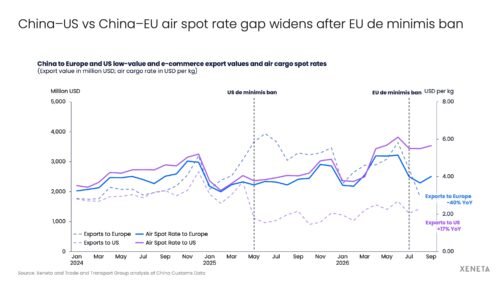
China’s low-value and e-commerce exports to Europe declined 40 percent year-on-year in August, according to Xeneta and Trade and Transport Group analysis of China Customs data. The decline followed a 25 percent drop in July.
The weaker volumes coincided with the introduction of the European Union’s €3 customs duty on individual items from 1 July.
China-US e-commerce exports followed a different trajectory. Volumes increased 17 percent year-on-year in August, as the market continued to recover after the removal of the US de minimis threshold in 2025. Xeneta noted, however, that the comparison remains against a lower base.
The divergence is beginning to show more clearly in freight pricing.
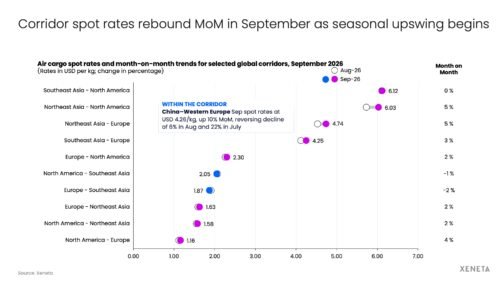
China-Western Europe airfreight spot rates climbed 10 percent month-on-month in September, reaching US$4.26 per kg. The increase reversed the declines seen in July and August. Xeneta attributed part of the September rebound to stronger outbound demand from China ahead of Golden Week.
Other major corridors also recorded renewed seasonal increases during September.
Rates between Northeast Asia and Europe rose 5 percent to US$4.74 per kg, while Northeast Asia-North America increased 5 percent to US$6.03 per kg. Southeast Asia-Europe rates gained 3 percent.
The transatlantic market also strengthened in both directions, with Europe-North America up 2 percent and North America-Europe up 4 percent.
Middle East disruption continues to support elevated rates
The strongest increases compared with late February continue to be concentrated on routes serving the Middle East.
By week 39, covering September 21-27, rates were 91 percent higher from South Asia and 80 percent higher from Europe than before the escalation of the Iran war.
Other major markets have also remained significantly above their late-February levels. Northeast Asia-North America rates were 34 percent higher, while Southeast Asia-North America rates stood 29 percent above their late-February levels.
According to Xeneta, the latter corridors are being supported by recovering e-commerce traffic as well as shipments connected to artificial intelligence infrastructure.
Europe-North America remains an outlier. Spot rates were still 20 percent below late-February levels, although the gap narrowed from 25 percent in August as summer belly capacity began leaving the market.
Xeneta sees a subdued final quarter
Despite stronger-than-expected demand growth during 2026, Xeneta expects the airfreight market to remain relatively subdued during the final quarter of the year.
“What will happen in Q4 is too early to call, but the indicators currently point towards a muted final quarter of the year,” van de Wouw said.
The ocean freight market could become an important factor in determining what happens next.
Persistent schedule unreliability, renewed disruption in the Red Sea and port congestion have pushed some Asia-US West Coast ocean rates back towards levels seen during the pandemic.
Should the gap in cost and reliability between ocean and air transport widen further, more shippers could move cargo from sea freight into airfreight.
For now, however, Xeneta has yet to see clear evidence of such a shift in its September figures.
“We are not yet seeing that in the September data,” van de Wouw said. “But it is the factor we are watching most closely.”