

The correction in the truckload market is still in its early stages, according to carrier executives who spoke at an investor conference this week, with the industry continuing to lose capacity amid regulatory pressure, weak economic conditions and rising operating costs.
A regulatory crackdown that began about a year ago has accelerated a contraction that was already underway. Prolonged economic weakness had pushed many small and midsize fleets out of the market, while the latest jump in diesel prices has added another burden for smaller operators, particularly those without mechanisms to recover higher fuel costs.
The U.S. Supreme Court’s broker liability ruling has added another layer of pressure. Both brokers and shippers are now being forced to take a closer look at the carriers they select, further narrowing the pool of available transportation providers.
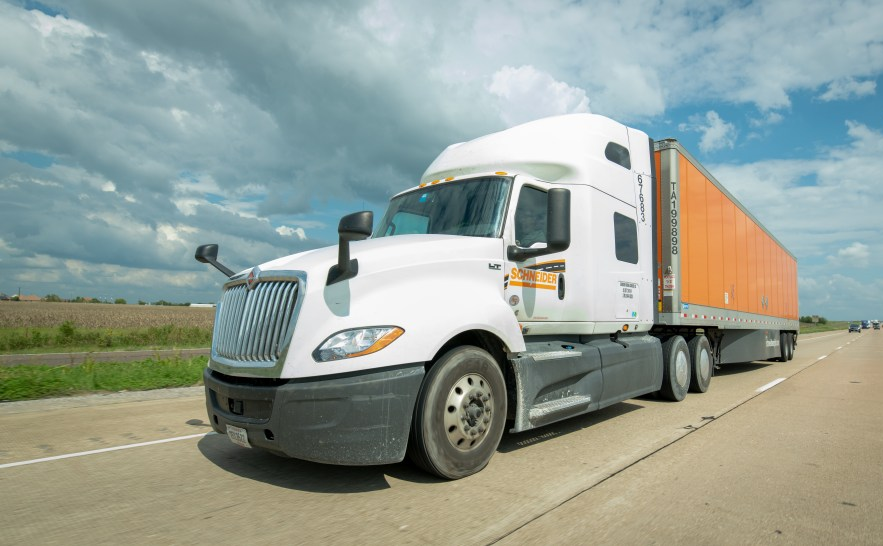
“There was no standard for entry-level driver training,” said Jim Filter, president and CEO of Schneider National (NYSE: SNDR), during Morgan Stanley’s Annual Laguna Conference.
Filter pointed to the thousands of drivers who entered trucking during the previous upcycle. According to him, many obtained operating authority unlawfully and did not receive adequate training. The closure of sham driver schools has since narrowed that entry point.
At the same time, capacity entering the market is facing greater scrutiny. Shippers and brokers are increasingly reluctant to tender freight to new motor carriers that do not have established safety ratings. Strict oversight of electronic logging device (ELD) providers is also making it harder for drivers to circumvent hours-of-service requirements.
These measures continue to eliminate drivers who, as Filter put it, “were not playing by the same rules as everybody else.”
Executives at Werner Enterprises (NASDAQ: WERN) described a similar shift in how carriers are being selected. They believe the current capacity crunch could still be only in the second or third inning, with the market tightening further after the Supreme Court’s broker liability, or Montgomery, ruling.
Werner’s management team also highlighted a recent Texas Supreme Court decision involving Home Depot (NYSE: HD). The retailer was dismissed from a liability lawsuit stemming from a fatal accident that occurred while Werner was hauling Home Depot cargo. The court ultimately determined that Home Depot had fulfilled its legal obligation by hiring a reputable carrier.
At Schneider, the brokerage operation has sharply reduced its approved carrier base. Filter said the list now contains about 14,000 carriers, down from 60,000 at its peak. The company began removing operators several years ago, initially as part of efforts to combat cargo theft.
“I can tell you that there aren’t 100,000 carriers out there that I think any of us would be able to look at and say, 100,000 carriers are safe and should be out there on the road,” Filter said.
The full consequences of the Montgomery decision are still emerging, but Filter expects a significant number of carriers to struggle to qualify for liability insurance. For others, insurance costs could become prohibitively expensive.
Werner also sees a potential opportunity in the disruption. As owning and operating private fleets becomes more difficult, the company believes some private fleets could be converted into dedicated customers.
Driver availability has once again become an issue. Private fleets often lack dedicated teams focused on recruiting and training drivers, while many expanded substantially during the pandemic and are now approaching their largest-ever equipment replacement cycle.
That replacement cycle comes at a time when equipment costs remain high. Private fleets are also dealing with continued increases in insurance costs and are increasingly being forced to consider self-insurance as a way to manage liability exposure.
Capacity, rather than demand, is becoming the bigger growth constraint
For Schneider, demand remains relatively stable, with certain areas showing strength. Minibid activity continues as shippers seek to protect transportation coverage ahead of their most important season.
But according to Schneider, demand itself is no longer the main obstacle to expansion. The bigger issue is whether sufficient capacity is available.
“Well, with the amount of supply that has exited, it has created enough demand for our services,” Filter said. “We don’t necessarily need more demand.”
Werner reported that demand among its predominantly discount-retail and food-and-beverage customers remained steady between the second and third quarters. The company is seeing increased minibid activity in its one-way business, while demand for dedicated services has also risen sharply.
For the third quarter, Werner expects one-way rates per total mile to increase between 10% and 13% year over year. The metric was already 10% higher year over year in the second quarter, while fleet utilization improved by 16%.
Its dedicated fleet, which represents 80% of Werner’s truckload network, is expected to generate a 3% to 5% year-over-year increase in revenue per truck per week for full-year 2026.
Revenue per truck per week increased 5% year over year in the second quarter, or 8% when FirstFleet is excluded. Werner acquired FirstFleet in January. The dedicated segment has also delivered low- to mid-single-digit contractual rate increases in recent months.
Werner expects the upcoming 2027 bid season could bring “strong” contract rate increases. The bid season is scheduled to begin within the next 30 to 60 days.
That timing could prove significant. Contract negotiations will take place during peak season, when the ongoing reduction in available capacity is expected to intensify the pressure on transportation supply.
Why it matters
The number of carrier options available to shippers is shrinking as stricter regulatory enforcement, higher fuel costs and insurance pressures continue to remove capacity from the truckload market.
For shippers, the changing landscape means navigating higher transportation costs, greater dependence on dedicated fleets and stronger competition for available capacity as the peak season approaches.