

There is an old truth in shipping that each generation seems to rediscover the hard way: whoever controls the ship ultimately controls the cargo’s destiny. In today’s environment of geopolitical chokepoints, sanctions and soaring war-risk premiums, commodity owners are rediscovering that principle with renewed urgency.
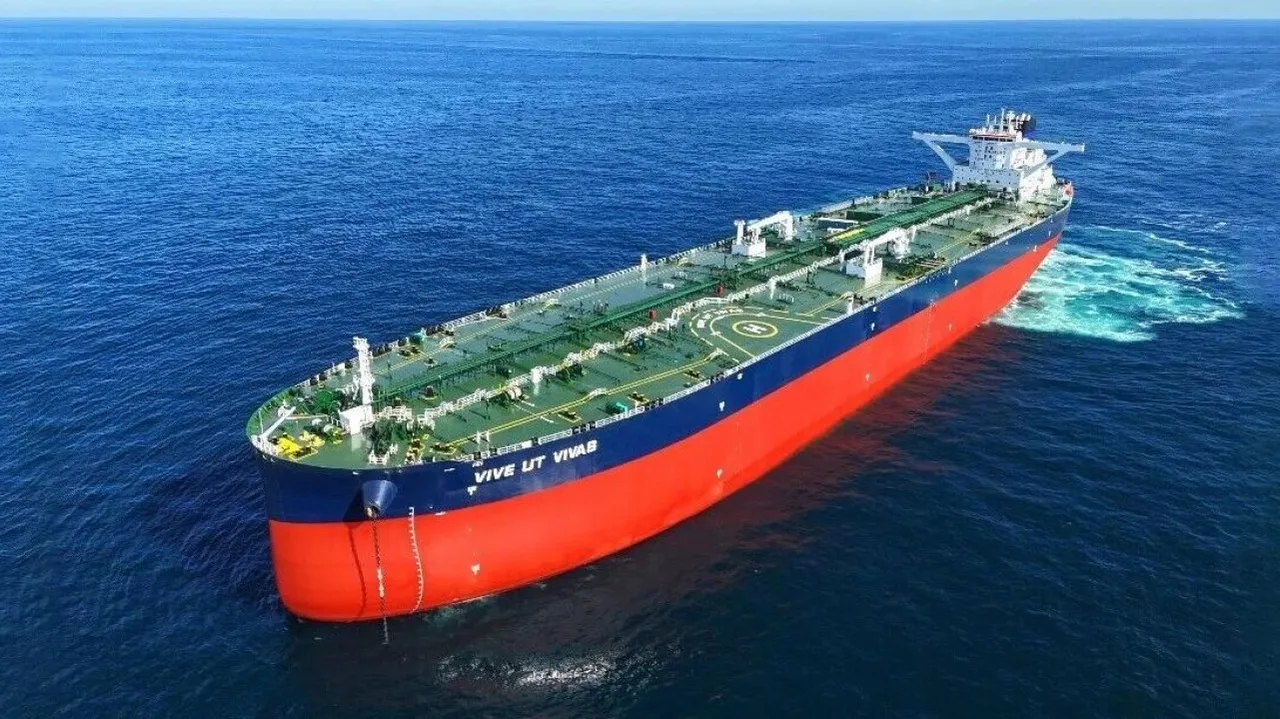
Abu Dhabi provides a clear example. In early August, ADNOC Logistics & Services announced the acquisition of five modern Very Large Gas Carriers and six Very Large Crude Carriers in a combined investment of approximately USD 1.3 billion. Nine of those vessels six VLCCs and three VLGCs were purchased on the secondary market for delivery in the third quarter of 2026 and are due to enter ADNOC service immediately upon delivery.
The move followed a previous order for four next-generation LNG carriers in July, worth approximately $900 million. Later in August, ADNOC exercised options for two additional LNG carriers from Jiangnan Shipyard for $444 million. Taken together, the company’s announced vessel acquisitions and newbuilding commitments in 2026 have reached approximately $2.7 billion.
The stated rationale is revealing. The ships are intended to support ADNOC Group’s integrated value chain as well as continued growth in production, trading and export volumes. In other words, a national oil company is deliberately putting its own steel beneath its own barrels.
Another major signal emerged on September 21, 2026, when Trafigura announced the creation of a new group company, Volare Shipping. The venture is designed to own, operate and scale a modern tanker fleet, beginning with six VLCCs already on the water and eight newbuildings on order. All of the vessels will be commercially managed by Trafigura’s own shipping business.
Volare is seeking approximately $500 million through a private placement ahead of a planned listing on Euronext Growth Oslo under the ticker “VLCC”.
The significance of the announcement is less about the fleet’s initial size than about the change in philosophy it represents. Trafigura has traditionally relied heavily on chartering rather than outright ownership, but its head of shipping, Andrea Olivi, has now argued that “owning the assets is a much better value proposition.”
The market environment helps explain that conviction.
The Strait of Hormuz crisis has driven tanker freight rates to record levels, with daily charter rates recently exceeding $1 million for the first time. Vessel supply has tightened as owners become increasingly reluctant to transit the Strait.
The impact is also being felt beyond the Gulf. Chartering a tanker from Venezuela to the US Gulf Coast now costs around US$5 per barrel, compared with US$1.90 previously. When freight can move by that magnitude, a trader without access to tonnage is also a trader without the same degree of leverage.
The final A in A.R.E.A.
This is exactly the kind of dynamic behind the A.R.E.A. framework: Alliances, Relationships, Execution and Assets.
The final “A” stands for Assets, and it reflects a straightforward reality of the geopolitical era. During periods of disruption, access to physical capacity ships, terminals and storage becomes a strategic moat.
A trading opportunity is of little value when the physical capacity required to execute it cannot be secured.
Commodity owners, oil companies and trading houses that own ships or maintain tight control over tonnage are therefore buying more than vessels. They are buying optionality, security of supply and a seat at the table when capacity becomes constrained by risk.
In the current environment, the movement by cargo owners into ship ownership is rational and, in many cases, smart.
But every strategy has a season. The question that too few boardrooms are asking is what happens to those assets when the season changes.
When the wars end, the inefficiency begins
Geopolitical disruption creates inefficiency, and that inefficiency creates freight premiums.
Longer voyages, avoided chokepoints, sanctioned trades, floating storage and owners unwilling to accept certain risks all consume additional tonnage and push rates higher. In that environment, owning ships can look like an exceptionally attractive strategy.
Now imagine the opposite scenario.
The disruption begins to ease. Hormuz normalises, whatever that eventual normality may look like. The Red Sea reopens. Sanctions are relaxed. Voyages become shorter. Tonnage that had been tied up returns to the market.
Freight rates fall.
That is when a captive fleet owned by a commodity company can begin to face a structural problem.
A specialist ship operator survives on efficiency. It can triangulate voyages, minimise ballast legs, combine cargoes from different charterers, time the market and manage its fleet with precision.
A captive fleet operates differently.
Its ships are primarily structured around the cargo book of one owner. They are deployed first to serve the parent company’s flows, even when that creates ballast legs that a third-party operator would never accept. Employment decisions can then be driven by internal priorities rather than by the strongest signals coming from the market.
That is where a much deeper risk emerges: cannibalisation.
Captive vessels will naturally be assigned to the parent company’s cargoes. In a normal market, those same cargoes might instead have been offered to the most efficient operator at the lowest available freight.
The commodity owner may therefore end up paying itself a higher effective freight than it would have paid in the open market.
The ship is technically “employed”. The shipping unit’s P&L may look respectable because of internal transfer pricing. Yet the underlying inefficiency has not disappeared.
It has simply migrated into the cost of the commodity.
Inefficiency does not disappear, it hides
This is the central concern.
For a commodity trading house generating revenues measured in hundreds of billions, a few extra dollars per tonne in freight costs can appear almost irrelevant. The additional expense can be absorbed into the trading margin, offset by a successful arbitrage or buried within the enormous balance sheet supporting the broader commodity business.
No one necessarily loses their job because of it. In many cases, no one even notices it.
But inefficiency does not vanish.
It changes address.
An unnecessary ballast leg, an under-utilised vessel or an internal freight rate above what the market would have charged all remain costs somewhere within the supply chain.
Eventually, those extra costs feed into the delivered price of the commodity.
And in many cases, the person who ultimately absorbs that cost is not the shipping division or the commodity trader. It is the final consumer at the petrol pump, through the electricity bill, in the price of steel and in the cost of the products built from it.
That is why oil companies and commodity traders owning ships can be a sound strategy during a crisis, but they must remain disciplined enough to ensure that inefficiency does not become invisible inside a much larger commodity balance sheet.
The Valemax lesson
Shipping has already provided a powerful example of how this dynamic can play out.
The Valemax vessels were conceived to reduce the cost of transporting iron ore from Brazil to China and help Vale compete with Australian producers located much closer to the world’s biggest iron ore market.
From a technical standpoint, the 400,000 dwt concept was impressive.
Vale ordered 12 of the vessels from Rongsheng in 2008 and another seven from Daewoo in 2009. Additional vessels of the same general type were later built for other owners and chartered to Vale under long-term contracts.
But what followed demonstrated the complications that can arise when a cargo owner steps directly into the shipowner’s arena.
When the first Valemax arrived at Dalian in December 2011, the China Shipowners’ Association mounted a strong response. It raised concerns over safety and port standards and accused Vale of seeking to monopolise the seaborne iron ore trade into China.
By September 2014, a Valemax had called at a Chinese port only twice.
The ships were instead pushed into floating transhipment operations in Malaysia or the Philippines, a development that effectively undermined the business model originally built around them.
Eventually, Vale returned the steel to the shipping industry.
The company sold four VLOCs to Cosco for $445 million under an arrangement in which Cosco would also build and operate 10 VLOCs under a 25-year contract of affreightment. Similar arrangements were subsequently reached with China Merchants.
By December 2017, Vale had sold all 19 of the Valemaxes it owned as part of a broader strategy aimed at strengthening its balance sheet and concentrating on core assets.
The important point is what did not happen.
The vessels did not disappear.
The Valemax concept itself did not fail.
Those ships still operate today.
What changed was ownership and operational responsibility.
Vale retained control over its logistics through long-term contracts of affreightment, while ownership, operation and market risk moved back to specialist shipping companies.
That is, in my view, the enduring lesson: shipping companies and shipping professionals are generally best placed to do what they specialise in shipping the cargo.
Owning without losing the discipline
None of this means that commodity owners should avoid owning ships altogether.
It means they need to own those assets with the discipline of a shipowner, rather than with the convenience of a cargo owner.
Several principles are particularly important.
First, ring-fence the shipping business and hold it to market rates.
Every internal fixture should be measured against what the best third-party operator would have charged.
A separately listed vehicle such as Volare, which is open to outside investors and subject to public scrutiny, moves in that direction because the market will expect the shipping economics to stand on their own rather than disappear within a wider commodity operation.
Second, let the fleet compete.
If a captive vessel cannot win the parent company’s cargo against the market, it should be deployed into the third-party market instead of displacing a cheaper alternative.
Third, plan the exit before entering the market.
A war premium is temporary, while a VLCC can remain in service for more than 20 years.
Ownership decisions made when rates are $1 million a day still need to make sense when rates are $40,000 a day.
Fourth, remember the other three letters in A.R.E.A.
Assets alone do not constitute a strategy.
Alliances with specialist shipowners, long-term Relationships through COAs and time charters, and disciplined Execution can often provide security of supply without forcing a commodity company to carry the entire burden of ownership.
Vale ultimately found its answer not by continuing to accumulate ships, but by creating stronger alliances around them.
Closing thought
Commodity owners should continue to act decisively to secure their supply chains in an increasingly turbulent world. But there is a danger in becoming so attached to the ships themselves that they continue operating them long after the commercial logic that justified ownership has disappeared.
Control is strategic.
Ownership is a tool.
Efficiency, ultimately, is a public good because when that efficiency is lost, the cost does not disappear.
It eventually reaches the consumer.