

October Brings a Recovery in Asia–Europe Spot Rates
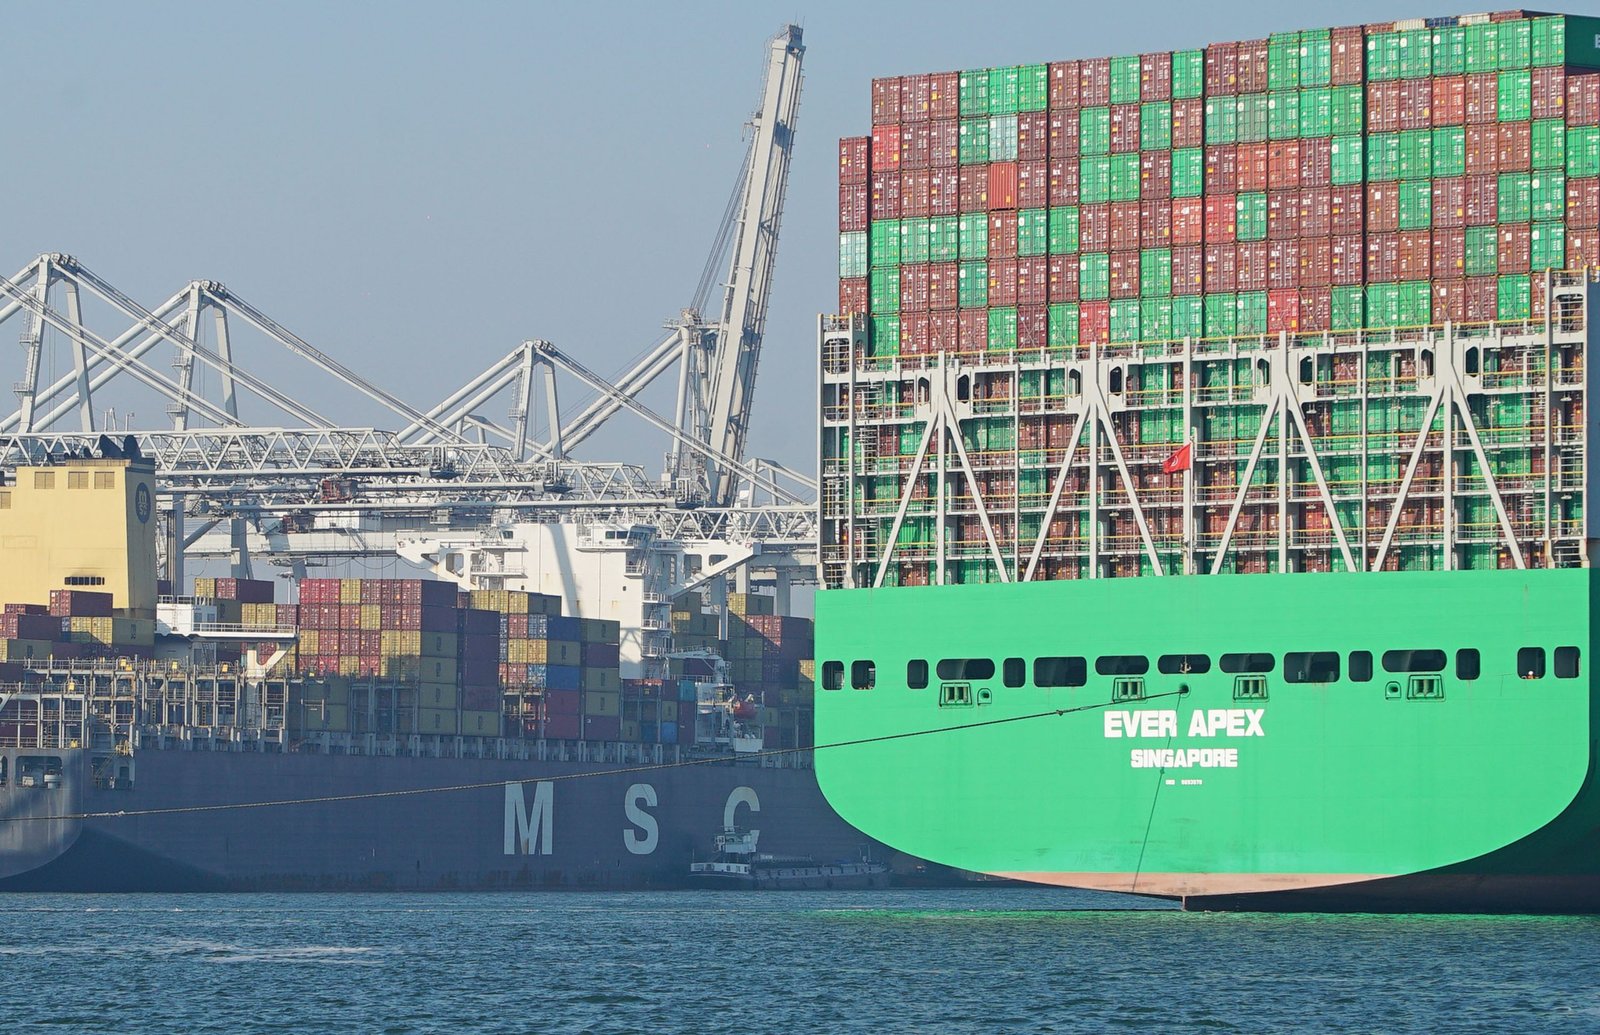
Container spot rates on routes from Asia to Europe have resumed their upward trajectory after reaching a low point at the end of September. The recovery has continued despite the Golden Week slowdown in China and the accelerated return of vessels to the Red Sea and Suez Canal route.
According to data from Xeneta, spot rates from the Far East to North Europe rose by 6.8% week on week, reaching $3,698 per FEU. Rates to the Mediterranean increased by 5.8% over the same period, settling at $4,442 per FEU.
The increases come as additional vessel capacity returns to the shorter Red Sea and Suez Canal route, easing some of the capacity constraints that have affected global shipping.
However, the expected downward pressure on freight prices has yet to materialise. Peter Sand, Chief Analyst at Xeneta, highlighted the apparent contradiction between rising available capacity and continuing rate increases.
According to Sand, spot rates remain 67% higher on routes to North Europe and 33% higher on Mediterranean routes than they were before the Hormuz crisis on 28 February.
European Demand Helps Lift Freight Prices
“Demand for goods coming into Europe is strong and that is supporting the market despite the extra capacity coming on stream. Sand pointed out that in the first seven months of the year, European import demand increased by 12.2% compared with the same period in 2025.
The demand has supported spot rates from falling even as more vessels return to the Red Sea corridor.
Upward pressure on prices also comes from the carriers’ capacity management. Drewry Shipping Consultants said the number of canceled sailings had risen from two the week before to eight booked for the coming week.
Carriers were reducing available capacity with blank sailings to support higher freight rates, Drewry said in its weekly freight rate report.
At the same time, the operating conditions at Shanghai have improved. Average vessel waiting times at the port had more than halved over the week, falling from 97 hours to 42 hours, Drewry said.
“Disruptions, including the Middle East conflict, can create volatility and sudden shocks to the market,” Sand said. But there is a strong driver of freight rates, and that is demand. With insufficient demand, prices would be vulnerable to a steep fall, but strong volumes of cargo bound for Europe have so far offset the additional capacity returning to the market.
Transpacific Rates Remain High But Signs of Stabilization Emerge
On the Pacific, spot rates on headhaul routes to the United States were broadly stable, rising just 0.2% to both the West Coast and East Coast.
Rates climbed to $8,311 per FEU for US West Coast shipments and $11,525 per FEU for East Coast cargo. Both routes, however, remain priced significantly higher than pre-Hormuz crisis levels, up 342% and 335% respectively since February, despite limited weekly movement.
But the latest figures indicate demand growth on transpacific routes may be leveling off, with freight rates showing signs of stabilizing.
However, carriers are still managing capacity on these trades. There were two more sailings canceled in the latest week, although this was down from six blank sailings in the week before.
East-West Shipping Routes Still Undecided
“Security risks and attacks on ships continue to affect vessel movements through the Gulf and uncertainty remains in the East-West container freight market,” Drewry said.
Transpacific freight rates are still being buoyed by US import demand, while carriers are working to hold rates on Asia-Europe routes through capacity adjustments and surcharges.
The diverging trends in the two major trade corridors reflect the different forces at play in the container shipping market. There is a strong demand on Asia–Europe routes, coupled with a deliberate capacity management to help sustain the recovery in spot rates. Prices on the other side of the Pacific are still high, but the small weekly gains hint at a market that may be entering a more stable period.
Freight rates will continue to be shaped by the balance between cargo demand and vessel capacity available, carrier pricing strategies and the security situation affecting key maritime routes.