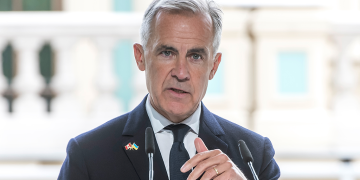


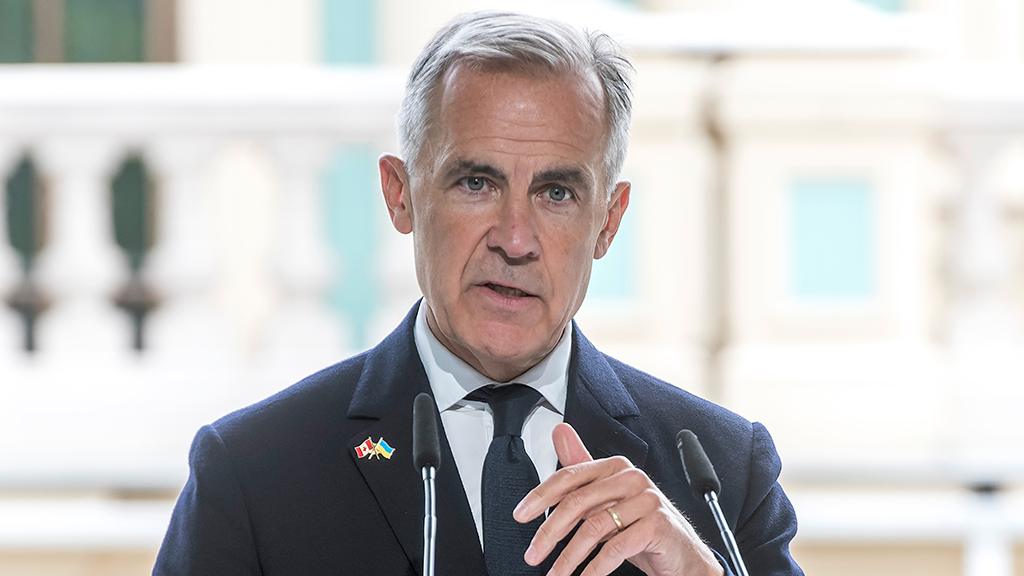
The federal government is introducing a new tax incentive aimed at encouraging businesses to increase investment, with Prime Minister Mark Carney announcing the measure as part of the Canada Investment Summit taking place in Toronto.
Known as the “productivity mega deduction,” the new incentive will significantly expand the share of assets eligible for the deduction. Coverage will rise to more than 65 per cent, compared with roughly 15 per cent today.
The expanded list of eligible assets includes fibre-optic cable, mining property, oil and gas pipelines, software, rail track and bridges, among other investments.
Ottawa estimates that the new deduction will have a fiscal cost of $36 billion over five years, beginning this year.
The federal government is also moving to make immediate expensing permanent, allowing businesses to recover the costs of qualifying investments sooner.
According to Ottawa, the combination of the measures will reduce Canada’s marginal effective tax rate on new business investment to 6.4 per cent, down from 13 per cent.
The government says the changes are intended to strengthen the investment environment and support greater business spending on productive assets across the Canadian economy.